

Blogs
Bromine Market 2026: Why 5.5% CAGR and Asia’s 1.23B Demand Shift the DNA of Global Competition
By PW Consulting, 2026-09-21
Bromine Market Outlook 2026–2032: Strategic Shifts and Commercial Opportunities
Market Overview and Core Challenges
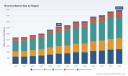
The global bromine market is entering a phase of measured but structurally significant growth. Revenues expanded from approximately $2.2 billion in 2020 to an estimated $3.1 billion in 2025, with forward indicators pointing toward a sustained annual growth rate of roughly 5.5 percent through 2032. By the end of the forecast period, total market value is projected to exceed $4.4 billion. This trajectory reflects more than cyclical recovery; it signals a market being reshaped by diverging regional supply realities, tightening environmental controls, and shifting demand patterns across industrial, energy, and specialty chemical end-use sectors.
Despite the positive top-line momentum, the market faces a set of interconnected challenges that reward strategic foresight rather than passive participation. Three structural pressures stand out as particularly consequential for commercial decision-making.
First, supply concentration and geographic vulnerability continue to define market stability. Bromine extraction relies heavily on natural brine deposits that are inherently localized. Operations tied to a few major basins face disproportionate exposure to regulatory shifts, resource management constraints, and geopolitical friction. When supply from these nodes is interrupted or restricted, downstream manufacturers and formulators experience cost variability and procurement uncertainty that cannot always be smoothed through inventory alone.
Second, environmental and operational regulations are increasingly reshaping production economics. Jurisdictions with significant brine processing capacity have moved to tighten oversight of extraction and handling practices. These measures are necessary from a sustainability and safety standpoint, but they also introduce compliance costs, operational pauses, or capacity reductions that ripple through the supply chain. The result is a market in which price stability is less a function of raw commodity dynamics and more a function of regulatory resilience and operational adaptability.
Third, demand is bifurcating in ways that complicate long-term planning. Traditional applications tied to industrial formulations and energy services remain foundational, yet growth is increasingly concentrated in specialty and pharmaceutical pathways. Companies that depend on a single demand profile are more exposed to substitution pressure, margin compression, or regional policy swings. The market now favors players who can navigate between steady bulk demand and higher-value, specification-sensitive applications.
These challenges do not undermine the market’s growth narrative; they clarify it. The opportunity lies in recognizing that bromine is transitioning from a largely commoditized input to a more strategically managed material where supply security, regulatory readiness, and application-specific differentiation determine competitive advantage.
Key Drivers of Market Change
Innovation and Product Specialization
Technological progress in bromine chemistry is steadily expanding the value that end-users can extract from bromine-based compounds. Rather than competing purely on volume, leading manufacturers are investing in higher-purity grades, controlled derivative portfolios, and application-tailored formulations. This shift matters because downstream sectors increasingly demand consistency, contaminant control, and reproducible performance, especially where bromine acts as a building block in complex synthesis pathways.
The trend is visible in pharmaceutical and fine chemical production, where bromine-derived intermediates support the synthesis of active ingredients used in sedatives, antiseptics, and oncology-related therapies. As drug manufacturing scales in major production hubs, the need for reliable, specification-grade bromine inputs grows in tandem. Companies that can supply with consistent purity and documented quality controls are gaining preference over those competing primarily on base price. In this context, innovation is less about dramatic breakthroughs and more about the cumulative value of precision, reliability, and technical support.
Regulatory and Policy Influence
Policy and regulatory developments are now central drivers of market behavior, not peripheral compliance issues. Environmental oversight of brine operations has intensified in several regions, influencing production continuity and cost structures. At the same time, safety standards and handling requirements affect logistics, storage, and customer qualification processes. These forces create a market where regulatory agility has become a competitive asset.
The commercial implication is straightforward: producers and distributors that can demonstrate robust compliance frameworks, predictable operating practices, and transparent sourcing are better positioned to retain and expand customer relationships during periods of regulatory tightening. Conversely, operations that depend on lenient enforcement environments or have limited flexibility to adjust processes face higher risk of disruption and price instability. Regulatory change is therefore acting as a filter, rewarding disciplined operators and reshaping procurement preferences across the value chain.
Demand-Side Shifts in Energy, Construction, and Healthcare
Demand patterns are evolving on multiple fronts. In oil and gas drilling, bromine-based fluids remain important for well completion and operational performance, sustaining demand from energy service activity. At the same time, the flame retardant segment continues to anchor a substantial share of consumption, driven by ongoing requirements in electrical equipment, building materials, and transportation components. These applications benefit from long-lived infrastructure and equipment cycles, providing a stable baseline for market activity.
Beyond these core uses, healthcare and specialty chemical demand is becoming increasingly influential. Growth in pharmaceutical manufacturing, together with rising interest in bromine-based intermediates for targeted chemical synthesis, is expanding consumption among formulators and producers seeking higher-value output. This does not replace traditional demand, but it alters the composition of growth. Companies that can serve both bulk industrial needs and specification-driven specialty applications are capturing a broader set of revenue opportunities than those locked into a single demand channel.
Supply Chain and Cost Structure Dynamics
Cost structures in the bromine market are increasingly shaped by location-specific factors rather than uniform global benchmarks. Production tied to stable domestic feedstock and favorable operating conditions can offer a meaningful buffer against international price volatility. By contrast, supply dependent on distant or constrained brine sources may be more exposed to energy costs, logistics complexity, and operational interruptions.
This divergence has practical consequences for procurement and production strategy. Buyers in regions with access to steady local supply are often better positioned to manage cost predictability, while those reliant on international flows must account for geopolitical, regulatory, and logistical risk in sourcing decisions. For producers, the implication is that cost leadership is no longer purely a function of scale; it also depends on securing resilient feedstock access, optimizing handling and transport, and maintaining operational continuity under changing environmental and policy conditions.
Competitive Landscape and Leading Strategies
The bromine market is concentrated among a group of well-positioned producers and specialty suppliers, with the top three firms accounting for roughly two-thirds of market share and the top five approaching four-fifths. This concentration reflects the capital intensity of brine-based extraction, the technical requirements of derivative production, and the importance of long-term customer qualification in pharmaceutical and industrial applications. Yet the landscape is not static; it is evolving through investment partnerships, regional specialization, and increasing divergence between bulk suppliers and fine-chemical-focused entrants.
Albemarle Corporation stands out for its scale and breadth across elemental bromine and derivatives serving industrial and pharmaceutical markets. Its positioning benefits from integrated capabilities, established customer relationships, and a presence in regions that can help insulate certain buyers from global price volatility. ICL Group Ltd has built a strong identity around bromine and bromine-based compounds sourced from Dead Sea brines, emphasizing industrial solutions and derivatives. Its operations illustrate both the advantages and the vulnerabilities of geographically concentrated feedstock: strong cost and supply advantages under normal conditions, but heightened sensitivity to environmental and operational disruptions.
LANXESS AG and Tosoh Corporation represent important nodes in the value chain for flame retardants, organobromines, and fine chemical intermediates. Their relevance lies in the ability to connect bromine supply with downstream application requirements, particularly where performance specifications and chemical consistency are critical. Gulf Resources Inc. reflects the importance of regional brine-based production and export capacity, while TETRA Technologies Inc. reinforces the link between bromine supply and energy-sector applications. Tata Chemicals Limited and Hindustan Salts Limited highlight the growing role of Indian producers in serving industrial, technical, and specialty demand.
In parallel, a cluster of firms with stronger fine-chemical and pharmaceutical orientations is gaining relevance. Archean Chemical Industries Ltd. has established a notable position in liquid bromine supply with high-purity offerings for pharmaceutical use. Jordan Bromine Company Ltd. operates as an exclusive regional producer serving industrial and pharmaceutical applications, and its strategic connection with broader regional partners underscores the role of investment alignment in capacity expansion. Chemada Fine Chemicals, Solaris ChemTech Industries Ltd., and Agrocel Industries Pvt. Ltd. illustrate how specialized manufacturers are carving out value in pharmaceutical, agrochemical, and intermediate segments by focusing on precision, customer-specific requirements, and application knowledge rather than competing solely on commodity terms. Honeywell International Inc. further rounds out the landscape as a supplier of bromine-based products and derivatives for industrial chemicals and performance materials, reinforcing the breadth of demand across multiple end markets.
PW Consulting
The strategic takeaway is that competitive advantage in this market is increasingly multidimensional. Scale remains important, but differentiation is coming from supply reliability, purity and quality assurance, regional reach, and the ability to serve both industrial and specialty pathways. Recent developments reinforce this direction. In January 2025, Arab Potash Company and Albemarle Corporation signed a joint investment agreement to expand bromine production capacity at Jordan Bromine Company, signaling that capacity growth is being pursued through partnership structures that combine regional resource access with established technical and commercial capabilities. Meanwhile, the July 2025 launch of Ipratropium Bromide Nasal Solution by Lupin Limited in the United States illustrates how bromine-based pharmaceutical products continue to enter competitive markets in forms that demand consistent raw material quality and regulatory readiness upstream.
Looking forward, the market is likely to see both consolidation and targeted fragmentation. Consolidation may continue where scale, feedstock access, and integrated derivative capabilities create durable advantages. Fragmentation is equally plausible in fine chemicals and pharmaceutical intermediates, where smaller or more specialized producers can compete on purity, customization, and technical service. New entry will probably remain limited at the raw extraction level due to resource and regulatory barriers, but value-added derivative production and application-specific formulation remain open avenues for disciplined players.
Future Trends and Commercial Implications
Trend 1: Supply Resilience Will Become a Primary Commercial Differentiator
Over the next three to five years, customers are likely to place increasing weight on suppliers that can demonstrate predictable continuity, transparent sourcing, and the ability to absorb or mitigate disruptions. This is not simply a procurement preference; it reflects the reality that brine-based supply is exposed to environmental, operational, and geopolitical variables. Companies that invest in diversified supply relationships, contingency planning, and clear quality documentation will be better positioned to secure long-term contracts and preferred-supplier status.
Lithium Bromide Market
For commercial players, the opportunity lies in building credibility around reliability. This can include strengthening regional supply options, improving inventory and logistics planning, and offering downstream customers clearer visibility into sourcing and handling practices. In a market where disruption risk is a meaningful cost driver, reliability can command preference even when base pricing is not the lowest.
Trend 2: Growth Will Accelerate in Specification-Sensitive and Specialty Applications
The next phase of market expansion is expected to lean increasingly on demand that requires higher purity, tighter controls, and stronger application support. Pharmaceutical synthesis, fine chemicals, and selected specialty industrial uses are natural beneficiaries of this shift, especially as manufacturing activity in major chemical-producing regions continues to expand. This trend favors suppliers and intermediaries that can provide consistent grades, technical collaboration, and responsive service rather than those operating purely as volume sellers.
Commercially, this suggests that revenue growth may be increasingly tied to value-added positioning. Companies that align product portfolios with specification needs, support customer qualification processes, and maintain strong quality systems can capture share in higher-margin segments. The broader implication is that bromine’s commercial relevance will depend not only on how much is produced, but on how effectively it is adapted to demanding downstream requirements.
Trend 3: Regional Divergence Will Shape Pricing, Risk, and Sourcing Strategy
Market participants should expect continued divergence between regions with stable, well-controlled production environments and those facing tighter regulatory or operational constraints. This divergence will influence not only price levels but also risk premiums, contract structures, and sourcing strategies. Buyers who depend on a single geography or a narrow supplier base may face greater exposure to localized disruptions or policy shifts, while those with flexible sourcing and regional alternatives can manage volatility more effectively.
Worldwide Bromobenzene Market
The strategic opportunity here is to treat geography as a risk-management variable rather than a background detail. For procurement teams, that may mean broadening supplier options, qualifying alternate sources, and aligning contract terms with continuity requirements. For producers and distributors, it may mean emphasizing regional stability, operational resilience, and service consistency as part of the commercial proposition.
Risks and Uncertainties to Watch
Several uncertainties could alter the pace or shape of these trends. Regulatory actions affecting brine operations may tighten further, creating additional constraints on production in certain regions. Geopolitical tensions and conflict-related disruptions can affect transport, feedstock access, and operating confidence, particularly where supply is concentrated. Demand could also evolve faster or slower than expected if substitution technologies advance in flame retardants or if energy-sector activity changes materially. Finally, quality and compliance expectations in pharmaceutical and specialty applications may rise, increasing the cost of entry for suppliers that cannot meet stricter requirements. These uncertainties do not cancel the market’s growth outlook; they make strategic preparedness essential.
Strategic Actions for Decision Makers
For Manufacturers and Producers
Position portfolios for both continuity and specialization. Core industrial demand provides a stable base, but long-term advantage will increasingly come from higher-purity grades, reliable derivative supply, and the technical support that specialty customers require. Invest in quality systems, application-facing expertise, and supply contingency planning so that operational resilience becomes part of the commercial offer. Where feasible, pursue partnerships or capacity alignment that strengthen regional feedstock access without over-concentrating risk in a single basin or operating environment.
For Investors and Strategic Capital Players
Focus on resilience and segmentation rather than aggregate volume alone. The market’s growth is real, but the most durable value creation is likely to come from players that can manage supply risk, meet specification-sensitive demand, and operate with disciplined compliance and cost control. Evaluate exposure to region-dependent brine operations, the ability to serve pharmaceutical and fine chemical pathways, and whether a company’s differentiation rests on credible operational and technical advantages. Capacity expansion financed through partnerships may offer a more balanced risk profile than isolated scale bets, particularly where feedstock concentration and regulatory sensitivity are high.
For Procurement and Supply Chain Leaders
Treat bromine sourcing as a continuity and quality strategy, not just a price optimization exercise. Diversify supplier options where possible, qualify alternate supply routes for critical applications, and align contract terms with the need for stable delivery and documented quality. Forspecification-driven use cases, prioritize suppliers with strong traceability, consistent purity, and proven regulatory readiness. Building flexibility into sourcing can reduce exposure to regional disruptions and help stabilize total cost of ownership, especially when international supply is subject to environmental or geopolitical shocks.
The bromine market is moving toward a phase where strategic positioning matters as much as raw market size. Success will depend on how well organizations anticipate supply vulnerability, regulatory evolution, and the shift toward higher-value applications. For decision makers who need more granular segmentation data, regional cost dynamics, and tailored scenario planning, a detailed market study can provide the deeper commercial context required to translate these trends into specific action plans.
For detailed analysis of this topic, please visit the official page: Bromine Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Bimetallic Bandsaw Blade Market: Why 6.5% CAGR Reshapes Steel Cutting Growth to $860M
By PW Consulting, 2026-09-21
Navigating the Bimetallic Bandsaw Blade Market: Strategic Trends and Commercial Opportunities Through 2032
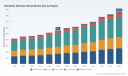
The global market for bimetallic bandsaw blades has entered a sustained growth trajectory, valued at approximately $555 million in 2025 and projected to expand at a compound annual growth rate of 6.5%, reaching nearly $860 million by 2032. This expansion is not merely a function of incremental industrial demand but reflects a structural shift in how manufacturers approach material processing, precision machining, and operational efficiency. Over the past half-decade, revenue climbed from $420.5 million in 2020 to $555.0 million in 2025, with consistent year-over-year gains signaling resilient underlying fundamentals. By 2028, the market is expected to surpass $664 million, and the upward momentum will continue through the end of the decade as automation, energy optimization, and advanced alloy requirements reshape procurement criteria. Understanding the forces converging on this niche but strategically vital segment is essential for executives, investors, and procurement leaders who must align positioning, capital allocation, and supply strategies with where the market is heading.
Two structural inflection points define the current landscape. First, the transition from general-purpose cutting tools to application-specific, high-performance blade architectures is accelerating, driven by tighter tolerances in metal fabrication, increased use of hardened alloys, and the need to minimize downtime in continuous production environments. Second, the industry is experiencing a concentration dynamic where a relatively small group of established manufacturers controls the majority of revenue, creating both a barrier for undifferentiated entrants and an opportunity for companies that can differentiate through tooth geometry, backing material engineering, or integrated service models. These forces do not simply shape pricing and shelf space; they redefine the competitive battlefield, where performance consistency, lifecycle value, and alignment with automated sawing systems increasingly outweigh commodity cost competition.
Key Drivers Shaping Market Trajectory
Technical Innovation and Material Science Breakthroughs
The durability and cutting performance of bimetallic bandsaw blades depend directly on the interaction between the high-speed steel cutting edge and the flexible alloy backing. Recent material developments have reinforced this value proposition. High-speed steel grades rich in molybdenum have advanced at a notable pace, strengthening wear resistance and heat tolerance in demanding metal cutting scenarios. This progression supports longer blade life, more stable cutting parameters, and reduced frequency of blade changes, which in turn lowers total cost of ownership for high-volume operations. Alongside alloy improvements, manufacturers are refining tooth geometry, set patterns, and substrate bonding processes to optimize chip evacuation, reduce vibration, and improve cut finish across varying material thicknesses. The practical implication is clear: blade selection is shifting from a transactional purchase to a performance engineering decision, with procurement teams weighing throughput, scrap rates, and machine compatibility alongside unit price.
Regulatory and Operational Pressures Toward Efficiency
Energy efficiency mandates and broader sustainability expectations in industrial operations are reshaping tooling choices. Metal cutting processes that consume less power per cut, maintain stable performance over extended runtimes, and reduce waste are increasingly favored in facilities subject to efficiency monitoring or carbon accountability frameworks. Bimetallic blades that deliver consistent cutting speeds with lower resistance and fewer remachining cycles align well with these priorities. Beyond energy, labor dynamics are influencing adoption patterns. Shortages of skilled operators in manufacturing environments have accelerated the uptake of automated bandsaw systems that rely on reliable bimetallic blades to sustain unmanned or semi-autonomous production runs. In this context, blade reliability becomes a bottleneck or an enabler of automation ROI, making performance predictability a strategic procurement criterion rather than a secondary specification.
Band Saw Blades Market
Market momentum is also reinforced by application diversity. Steel cutting remains a core demand center, supported by structural fabrication, maintenance, and heavy equipment production. Aluminum cutting continues to draw volume from automotive, aerospace, and general manufacturing workflows, where clean cuts and minimal material deformation are valued. Cast iron cutting serves niche but critical requirements in foundry and machinery remanufacturing contexts, while additional applications span specialized alloys and mixed-material processing. This breadth provides revenue resilience, as demand is not overly dependent on a single vertical, and it encourages blade suppliers to maintain differentiated product lines tailored to material-specific cutting characteristics.
Competitive Landscape and Strategic Positioning
Established Leaders and Differentiation Logic
The market features a mix of long-standing Western manufacturers and emerging Asian producers, each pursuing distinct routes to advantage. Companies such as Lenox Tools, M.K. Morse Company, and DoALL Sawing Products have built reputations around application-specific bi-metal blades for metal cutting, with product lines oriented toward high-production environments and general-purpose versatility. L.S. Starrett Company emphasizes advanced tooth geometry and geometry optimization to improve cut quality and blade stability, while Bahco positions around production-focused series designed for sustained cutting operations. German manufacturers bring specialized engineering depth: Wikus offers modified cutting materials and alloyed steel backing for alloyed steel applications, Eberle focuses on duoflex architectures for stainless steel, high-speed steel, and cast iron, and Honsberg targets a broad range of industrial applications with bimetal solutions. Simonds International LLC supports production, general-purpose, and structural steel cutting segments, rounding out a competitive field where brand trust, technical service, and consistent quality are central to customer retention.
On the supply side, Bichamp Cutting Technology Co Ltd represents the expanding presence of Chinese manufacturers focused on high-performance metal cutting, leveraging scale, cost competitiveness, and increasing technical capability to serve both domestic and export markets. This dynamic creates a bifurcated competitive environment: premium segments remain contested by manufacturers emphasizing engineering depth, application-specific performance, and service integration, while value-oriented segments face pressure from producers able to combine acceptable performance with lower procurement costs. The result is a market where differentiation is increasingly tied to measurable outcomes—blade life, cut consistency, compatibility with automated systems, and technical support—rather than brand alone.
Recent Industry Activity and Market Evolution
Company activity over the past year underscores the emphasis on application expansion, customer engagement, and technology visibility. In early 2025, Wikus hosted a targeted industry event focused on innovation for efficient steel processing, signaling a strategic interest in aligning blade performance with demanding production requirements. Later in the year, the company participated in trade shows highlighting bimetal bandsaw blades and sawing solutions for industrial sheet metal processing, and presented a bimetal blade tailored for wood industry applications, illustrating how manufacturers are exploring adjacent end-use contexts to broaden demand pools. These moves reflect a broader trend: leading players are not only refining core metal-cutting offerings but also testing cross-industry applicability, strengthening dealer and user relationships, and using live demonstrations to communicate performance advantages in concrete operating conditions.
PW Consulting
The competitive trajectory points toward modest consolidation in the premium tier, as larger manufacturers seek to broaden application coverage and strengthen regional distribution, while smaller or specialized producers may find growth by focusing on niche applications, custom geometries, or localized service networks. New entrants face a steep climb given the concentration of revenue among established names, but they can still carve positions through rapid customization, cost-efficient manufacturing, or targeted service offerings for underserved geographies and applications. The landscape is therefore evolving along two parallel paths: consolidation and brand elevation in high-value segments, and fragmentation with specialized solutions in niche or price-sensitive contexts.
Forward Outlook: Trends and Commercial Implications
Trend One: Automation-Ready Blades as a Standard Expectation
As automated and semi-autonomous bandsaw systems become more prevalent in response to labor constraints and throughput goals, blade specifications will increasingly be evaluated for compatibility with consistent feed rates, reduced variability, and extended runtime between changes. Manufacturers that design blades with automation in mind—stable cutting behavior, predictable wear patterns, and clear performance envelopes—will be better positioned to capture demand from facilities scaling automated sawing capacity. For suppliers, this creates an opportunity to bundle blades with system integration guidance, application engineering, and maintenance planning, shifting the conversation from unit price to uptime and process reliability.
Trend Two: Material-Specific Engineering as a Value Driver
Demand for differentiated performance across steel, aluminum, cast iron, and other materials will continue to reward suppliers that can deliver application-tuned tooth geometry, set design, and backing material characteristics. As more producers encounter mixed-material workflows or harder alloys, the ability to match blade architecture to material properties will become a decisive purchasing factor. This trend favors companies that invest in application testing, provide clear selection frameworks, and communicate lifecycle performance data. Commercial opportunity lies in developing documented performance benchmarks and helping customers translate material requirements into blade choices that reduce trial-and-error procurement.
Trend Three: Cost Structure Dynamics and Supply Chain Resilience
The interplay between raw material pricing, alloy availability, and manufacturing efficiency will remain central to margin management and pricing strategy. With certain high-speed steel grades trending upward in cost, producers must balance input cost pressures against the value delivered through longer service life and reduced downstream waste. Supply chain resilience—spanning specialty alloy sourcing, bonding process control, and logistics—will differentiate companies that can maintain consistent quality and delivery from those exposed to volatility. The strategic implication is straightforward: competitive advantage will accrue to firms that can stabilize input costs through forward sourcing, optimize manufacturing yield, and articulate total cost of ownership benefits that justify performance premiums where appropriate.
These trends carry both opportunity and uncertainty. On the opportunity side, the convergence of automation, efficiency mandates, and application-specific engineering expands the rationale for premium blade adoption and creates openings for service-led business models. On the risk side, macroeconomic swings in industrial production, fluctuations in alloy availability, and intensifying price competition in value segments could pressure margins and slow adoption in price-sensitive regions. Geopolitical factors affecting trade flows and raw material supply may also influence regional cost structures and availability, requiring flexible sourcing and clear communication of supply continuity plans.
Strategic Takeaways for Decision Makers
For blade manufacturers and tooling suppliers, the priority is to convert technical differentiation into commercially legible value. This means investing in application-specific validation, documenting performance outcomes in terms that procurement and operations teams can use, and aligning product roadmaps with automation compatibility and material-specific needs. Companies should also evaluate where service, technical support, and selection guidance can strengthen customer retention, particularly in markets where blade longevity and cut consistency directly affect production economics. Where cost competition is intense, clear positioning around total cost of ownership, downtime reduction, and application fit can help defend margins without resorting to undifferentiated price competition.
For investors evaluating exposure to this segment, the relevant signals are the durability of demand across multiple applications, the pace of automation-driven adoption, and the ability of leading manufacturers to sustain differentiation through engineering and service rather than volume alone. Concentration in the market suggests that scaled players with strong brand equity and application coverage may capture disproportionate share of incremental growth, while specialized or regionally focused companies can still generate attractive returns if they serve underserved applications or maintain a credible cost-to-performance ratio. Due diligence should assess supply chain exposure to specialty alloys, the credibility of performance claims, and the extent to which product portfolios are aligned with the shift toward automated and efficiency-conscious operations.
For procurement and operations leaders, the practical imperative is to treat blade selection as a process decision rather than a commodity purchase. Evaluating blades against actual material mixes, machine configurations, and throughput targets can reveal where higher-performance options reduce total cost through longer life, fewer cut defects, and better automation compatibility. Establishing clearer selection criteria, testing application-specific options in representative conditions, and engaging suppliers for technical guidance can improve procurement outcomes and reduce variability in sawing performance. In environments where energy efficiency, labor constraints, and production consistency matter, the blade choice can influence more than cutting quality; it can affect overall operating economics.
For organizations seeking a deeper dive into segment-level sizing, regional demand patterns, application split trends, and company-specific positioning, a comprehensive research report provides the granularity needed to translate these strategic themes into concrete plans. Detailed breakdowns by region, application, and type, along with company profiles and recent development tracking, enable more precise market-entry decisions, pricing strategies, and procurement frameworks. Accessing that level of detail allows decision makers to convert broad market direction into targeted actions, whether the goal is to expand product coverage, enter a new geography, refine a procurement specification, or assess investment exposure with greater confidence.
Worldwide Welded Band Saw Blades Market
For detailed analysis of this topic, please visit the official page: Bimetallic Bandsaw Blade Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Vector Network Analyzer Market: Why 3.38% CAGR and 67% CR3 Redefine Strategic Outlook
By PW Consulting, 2026-09-21
Vector Network Analyzer Market: Strategic Trends and Commercial Opportunities Through 2032
Market Landscape and Core Challenges
The Vector Network Analyzer (VNA) market operates at the intersection of precision measurement and high-frequency engineering, serving as a critical enabler for telecommunications, aerospace engineering, and advanced electronics manufacturing. After a period of steady expansion, the market reached approximately 0.44 billion USD in 2025, building on a trajectory that saw moderate growth through the early 2020s. Over the forecast horizon through 2032, the market is projected to advance at a compound annual growth rate of 3.38 percent, with revenue scaling toward 0.56 billion USD by the end of the period. This growth profile reflects a mature, specialized instrumentation sector where incremental expansion is tied closely to broader technological adoption cycles rather than standalone product demand.
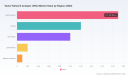
Market concentration remains notably high, with the top three participants commanding roughly two-thirds of total revenue and the top five players accounting for approximately 84 percent. This concentration underscores the technical barriers to entry, the importance of established calibration and certification ecosystems, and the long procurement cycles typical of enterprise and institutional buyers. At the same time, the distribution of revenue across technology classes and end-use sectors reveals where the market’s weight truly sits. Lower-frequency instruments in the 0-to-10 GHz range dominate share, while higher-frequency segments above 50 GHz remain relatively small in absolute terms but strategically important for next-generation applications. Communications continues to represent the largest application bucket, with automotive, electronic manufacturing, and aerospace and defense each contributing meaningful but more modest shares. Regionally, North America leads in revenue contribution, followed by Europe and Asia Pacific, with Latin America and the Middle East and Africa representing smaller but emerging pockets of activity.
Worldwide 5G Analyzer Market
Against this backdrop, three core challenges define the current inflection point. First, the cost and complexity of high-frequency development create a persistent barrier. Designing and calibrating VNAs for operation above 15 GHz demands substantial research and development investment, while premium components and high-speed data acquisition systems further increase production expenses. These cost dynamics constrain product accessibility and place pressure on vendors to justify performance premiums in customer conversations. Second, the market must navigate a shifting compliance and standardization environment. As RF testing becomes more tightly integrated into 5G, IoT, and Industry 4.0 deployment requirements, precision and traceability are no longer optional attributes; they are procurement prerequisites. Accredited calibration laboratories and standardized measurement protocols are increasingly baked into purchasing decisions, raising the stakes for both established players and new entrants. Third, the market faces a segmentation tension between broad-coverage, mid-range instruments and specialized high-frequency or portable solutions. Buyers want flexibility, but vendors must balance feature expansion against size, weight, power, and cost constraints. Solving this tension will separate growth-oriented vendors from those stuck in the middle.
Key Drivers Shaping Market Direction
Technological Innovation and Measurement Capability Expansion
Innovation in VNA architectures is expanding what practitioners can measure in the field and in the lab. Recent product moves illustrate this trajectory clearly. In September 2024, Keysight Technologies introduced the NA520xA PNA-X Vector Network Analyzer, configured with four RF sources, two internal combiners, and two low-noise receivers. This configuration reflects a broader push toward multi-dimensional characterization, where faster sweep capability, improved signal-to-noise performance, and integrated test configurations reduce the need for external mixing hardware. For engineering teams, such architectures translate into shorter test cycles and more compact bench setups, which matters as product development timelines tighten across communications and electronic manufacturing.
A complementary innovation thread is the extension of VNA functionality into field-portable instruments. In May 2025, Anritsu added Vector Network Analyzer and Vector Voltmeter measurements to its Site Master field portable instruments. This move blurs the line between bench-grade analysis and on-site troubleshooting, enabling technicians to capture vector-level data outside controlled laboratory environments. The strategic implication is significant: as deployment and maintenance activities move closer to real-world infrastructure, portable precision becomes a differentiator rather than a niche convenience.
Beyond individual product launches, two structural cost and capability dynamics continue to shape innovation incentives. High development and calibration costs for high-frequency operation above 15 GHz require substantial R&D investment, reinforcing the advantage of vendors with deep component expertise and established calibration infrastructure. At the same time, premium components and high-speed data acquisition systems increase production expenses, which keeps price-performance positioning under constant scrutiny. Vendors that can modularize performance, offer tiered configurations, or shift complexity toward software and calibration workflows are better positioned to absorb these cost pressures while preserving margin.
Policy, Regulation, and the Calibration Imperative
Regulatory and standards-driven expectations are increasingly shaping procurement behavior. Precision RF testing is now tightly coupled to compliance requirements in 5G, IoT, and Industry 4.0 applications, making VNAs essential tools for demonstrating that devices meet spectral, impedance, and linearity expectations. This is not merely a technical requirement; it is a commercial one. Buyers in regulated industries and supply chains are more likely to require evidence of traceable measurements, accredited calibration support, and documented measurement integrity.
This environment rewards vendors with recognized calibration ecosystems. For example, calibration laboratories associated with major instrumentation providers have been accredited in accordance with the ISO/IEC 17025 standard, reinforcing the value of standardized, auditable measurement workflows. For enterprise buyers, such accreditation reduces risk in qualification processes and simplifies supplier evaluation. For vendors, it creates a defensible moat: once a calibration and compliance pathway is embedded in a customer’s procurement process, switching costs rise, and relationship durability improves.
Demand-Side Shifts Across Communications, Automotive, and Advanced Manufacturing
Demand growth is being shaped less by any single application surge than by the broadening use of RF characterization across multiple sectors. Communications remains the largest application anchor, driven by continuous network evolution and the need to validate antenna systems, filters, and front-end components. Yet the more strategically interesting story is the diffusion of VNA use into adjacent domains. Automotive electrification and advanced driver-assistance systems increase the need for component and subassembly validation. Electronic manufacturing relies on VNAs for quality assurance and process control as circuit designs become more sensitive to impedance mismatches and parasitic effects. Aerospace and defense continue to represent a steady, requirements-driven demand base where high-reliability measurement and traceability are non-negotiable.
A parallel demand-side shift is the growing preference for deployable measurement solutions. Field technicians, line engineers, and distributed test teams increasingly expect instruments that are lighter, easier to power, and simpler to calibrate in non-ideal environments. This is where smaller-footprint, USB-powered, and calibration-module-supported designs gain relevance. The demand signal is not that every application requires a portable solution, but that a meaningful subset of use cases rewards reduced setup burden and faster time to measurement. Vendors that align product portfolios to this operational reality can open new customer segments without necessarily competing head-to-head in flagship laboratory instruments.
Supply Chain and Cost Structure Dynamics
The VNA market is affected by the same broader considerations that influence precision electronics: component availability, manufacturing complexity, and the cost of maintaining high performance at elevated frequencies. Premium components and high-speed data acquisition systems raise production expenses, while high-frequency calibration and validation compound the cost of bringing products to market. These factors do not necessarily cap growth, but they do shape how growth is captured. Vendors with stronger supply chain leverage, more efficient calibration workflows, and the ability to standardize subsystems across product families can better manage cost inflation and preserve competitive pricing.
At the same time, the market’s concentration pattern suggests that scale advantages matter. With the top five participants representing a substantial majority of revenue, established players can amortize R&D, calibration infrastructure, and support operations across broader installed bases. Newer or smaller vendors must therefore find defensible positions through specialization, portability, ease of use, or targeted application support rather than attempting to out-invest incumbents across the full performance spectrum.
Competitive Landscape and Leading Strategies
Positioning Among the Leading Participants
The market’s leadership group reflects distinct strategic emphases, each aligned to different buyer priorities. Keysight Technologies continues to emphasize high-performance bench architectures, with its NA520xA PNA-X and VectorStar/Streamline families positioning around multi-source flexibility and advanced receiver configurations. The strategic signal here is clear: Keysight is investing in measurement depth and configuration versatility for customers who prioritize characterization speed, signal integrity, and laboratory-grade performance. Its September 2024 introduction of the NA520xA PNA-X, with four RF sources, two internal combiners, and two low-noise receivers, reinforces an emphasis on reducing external hardware dependencies while expanding in-line test capability.
Rohde & Schwarz takes a different posture, focusing on broad frequency coverage and multiport scalability with offerings such as the ZNBT and ZVA families, including multiport VNAs extending up to 1.1 THz. This positions the company strongly in applications where frequency range, port density, and system integration matter more than compact portability. For buyers scaling test systems or requiring high-frequency coverage for advanced materials and component characterization, this breadth becomes a central value proposition.
Copper Mountain Technologies has carved out a pragmatic, accessibility-oriented position with 1-port and 2-port USB-powered VNAs supported by calibration modules. The strategic appeal lies in lower total cost of ownership, simpler deployment, and easier integration into distributed or resource-constrained environments. Rather than competing on extreme frequency or multi-source complexity, this approach targets customers who value fast setup, portability, and straightforward calibration workflows. It is a useful reminder that the market does not reward a single winning formula; it rewards fit-to-use-case.
Worldwide Vector Network Test Instrument Market
Anritsu combines field-portable capability with bench-class measurement expansion. Its VNA Master series and VectorStar/ShockLine families span a range of performance needs, while the May 2025 addition of Vector Network Analyzer and Vector Voltmeter measurements to Site Master field portable instruments illustrates a deliberate push to bring vector-level insight into field environments. This dual orientation gives Anritsu credibility in both installation/commissioning contexts and more detailed component characterization, allowing it to serve customer journeys that span lab and field.
How the Competitive Map Is Evolving
The landscape is not static. Several dynamics are reshaping how competition plays out. One is the continued consolidation of value among established players who can fund high-frequency R&D, sustain calibration infrastructure, and maintain global support networks. With market concentration already high, the Near-term question is less about dramatic market share rebalancing and more about how incumbents defend their positions through product refresh cycles, application-specific packaging, and service-grade differentiation.
A second dynamic is the emergence of sharper segmentation. Portable and field-deployable solutions are gaining visibility, while high-frequency laboratory systems remain essential but demanding. In between, vendors are experimenting with software-defined calibration, modular configurations, and tiered performance bundles. This suggests a market that is gradually moving away from one-size-fits-all positioning toward a portfolio logic where product families are designed around distinct workflows: bench characterization, field troubleshooting, production line verification, and specialized high-frequency research.
PW Consulting
A third dynamic is the role of compliance and certification as a competitive lever. In a market where measurement integrity is directly tied to product acceptance and regulatory alignment, vendors that can offer accredited calibration support and standardized documentation gain an advantage in enterprise and institutional sales cycles. This does not eliminate competition, but it raises the bar for entry and rewards organizations that treat calibration and traceability as strategic assets rather than back-office functions.
Outlook: Three Trends That Will Shape the Next 3 to 5 Years
Trend 1: Precision Testing Becomes Embedded in Broader Technology Deployment Cycles
VNA demand will increasingly be linked to the deployment cadence of 5G-related infrastructure, IoT scale-up, and Industry 4.0 automation. As these environments mature, the need for repeatable, traceable RF characterization will move from project-stage validation to ongoing maintenance and quality assurance. For vendors, this means opportunity lies not only in selling instruments but in enabling recurring workflows: calibration services, software-supported measurement routines, and application content that helps customers integrate VNAs into standard operating procedures. The commercial upside is sticky relationships and broader usage across the product lifecycle. The risk is that buyers may treat measurement as a commodity if differentiation is limited to hardware specifications alone.
Trend 2: Field-Portable and Accessible Form Factors Will Expand the Addressable User Base
Instrumentation that reduces setup burden, power requirements, and calibration complexity will continue to open opportunities beyond traditional laboratory buyers. USB-powered architectures, portable field instruments with vector-level capability, and calibration modules that simplify on-site workflows all point toward broader adoption among technicians, field engineers, and distributed production teams. This trend creates room for growth even in a market with modest overall CAGR, because it expands who can use VNAs and where they can be used. The risk is that ease-of-use offerings must still meet enough performance expectations to be trusted in serious characterization tasks. If portability comes at the expense of measurement credibility, adoption will stall.
Trend 3: High-Frequency and Multi-Port Capabilities Will Remain Strategic, Not Mass-Market
Above-50 GHz measurement and advanced multiport configurations will continue to matter disproportionately for certain applications, even if they represent a smaller share of total market revenue. In aerospace and defense, advanced materials research, and select communications roadmap items, high-frequency performance is a gating requirement. Vendors that can sustain leadership here will protect premium positions and high-value customer relationships. At the same time, the cost and complexity of high-frequency development above 15 GHz will keep this segment concentrated among players with strong R&D capacity and calibration maturity. The strategic opportunity is to use high-frequency leadership as an anchor for credibility while competing in broader segments through more accessible product tiers. The uncertainty is that demand for extreme-frequency instrumentation can be lumpy and dependent on specific program cycles, which makes revenue timing less predictable.
Strategic Implications for Decision Makers
For Instrument Manufacturers and Technology Providers
Product strategy should be guided by a clearer separation of use cases. High-performance laboratory systems, field-portable tools, and accessible mid-range instruments are not interchangeable; they solve different problems and carry different cost structures. Rather than stretching a single platform to cover every requirement, vendors can gain advantage by designing families that align with distinct buyer workflows and then integrating them through software, calibration support, and application documentation. Equally important is treating calibration and compliance support as marketable capabilities. In a market where measurement integrity influences purchasing decisions, accredited calibration pathways and standardized documentation can be as strategically relevant as raw frequency specifications. Finally, managing cost pressures from premium components and high-speed data acquisition will require disciplined modular design, shared subsystems, and efficient calibration processes.
For Investors and Strategic Partners
The VNA market offers stability more than explosive expansion, which makes selection of exposure points especially important. Given high concentration, the most direct path to market participation often runs through established players with strong calibration infrastructure, broad application coverage, and diversified product families. However, the most interesting differentiation may come from enabling layers: portable form factors, field-ready measurement workflows, software-assisted calibration, and application-specific packages that reduce friction for non-specialist users. Investment logic should therefore weigh not only headline revenue trajectory but also how well a company is positioned to capture value from recurring workflows, service attachment, and segmentation-driven expansion. The key uncertainty is that demand in high-frequency and program-driven segments can be uneven, so momentum should be evaluated across multiple application streams rather than a single headline driver.
For Procurement Leaders and Engineering Decision Makers
Purchasing decisions should begin with workflow reality rather than maximum specification. The right VNA choice depends on whether the priority is laboratory characterization depth, field portability, production line throughput, or compliance documentation. Buyers should assess not only instrument performance but also calibration support, accreditation alignment, and the practical burden of setup and maintenance. In regulated or supply-chain-sensitive environments, measurement traceability and standardized documentation can materially affect qualification risk. It is also worth considering total cost of ownership over the instrument lifecycle, including calibration, support, and the operational time required to bring the system into productive use. A slightly less ambitious specification that is easier to deploy and maintain can often deliver better business value than a higher-specification instrument that underutilizes its capabilities.
Closing Perspective
The Vector Network Analyzer market is entering a phase where growth will be shaped less by raw specification escalation than by how effectively vendors connect measurement capability to real-world deployment, compliance, and operational simplicity. The market’s steady expansion through 2032, combined with high concentration and clear segmentation across frequency ranges and applications, suggests a sector where differentiation will come from workflow fit, calibration credibility, and the ability to serve both laboratory and field environments. For manufacturers, the opportunity lies in portfolio logic and service-grade differentiation. For investors, the opportunity lies in identifying exposure to recurring value and accessible adoption pathways. For buyers, the opportunity lies in matching instrument capability to actual use cases while reducing qualification and maintenance risk.
Detailed segmentation data, regional and application-level revenue splits, company-level market share context, and forward scenarios are available in the full PW Consulting research report. That deeper dataset can support more precise sizing, competitor positioning analysis, and customized recommendations tailored to specific product plans, investment theses, or procurement requirements.
For detailed analysis of this topic, please visit the official page: Vector Network Analyzer (VNA) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Steel Grating Market at $227M: What the 3.61% CAGR Really Means for 2026-2032
By PW Consulting, 2026-09-21
Strategic Shifts and Commercial Opportunities in the Steel Grating Market
Market Landscape and Structural Challenges
The steel grating market has demonstrated consistent expansion over the past five years, with total market revenue growing from approximately 183.8 million USD in 2020 to 227.0 million USD in 2025. The trajectory continued into 2026, reaching 230.47 million USD, and forward projections indicate a climb to 289.39 million USD by 2032. This represents a compound annual growth rate of 3.61 percent across the forecast horizon. While the absolute growth rate may appear measured, the underlying composition reveals a market undergoing meaningful recalibration. Demand is no longer driven purely by replacement cycles or basic infrastructure spend. Instead, the market is being shaped by shifts in safety compliance, industrial modernization, and regional capacity realignments.
At the same time, the industry is navigating a set of structural challenges that will define competitive positioning over the next several years. One of the most pressing is the tension between raw material price volatility and margin preservation. Steel and aluminum input costs have experienced sharp fluctuations, with carbon steel price hikes placing direct pressure on manufacturing economics. These swings are not isolated events. They compound with rising non-raw material input costs, including labor and freight, which continue to escalate beyond initial commodity-driven increases. Producers that rely on static pricing models or long-term fixed contracts without effective pass-through mechanisms are being squeezed from both sides of the cost structure.
A second challenge lies in the evolving regulatory perimeter. Trade oversight has intensified, particularly regarding imported grating products. The United States International Trade Commission instituted five-year reviews for steel grating from China to assess whether continued dumping or subsidization warrants duty extensions. This development signals that trade policy will remain an active variable rather than a settled backdrop. Companies with heavy exposure to cross-border sourcing or those that have built cost advantages on imported feedstock must now factor in the possibility of renewed duties, supply route adjustments, and administrative review cycles. Regulatory shifts of this nature do not merely alter pricing. They reshape sourcing strategies, lead times, and risk allocation across the value chain.
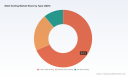
The third challenge is operational and strategic rather than purely financial. Market concentration data indicates that the top three players hold approximately 35.0 percent of total revenue, while the top five capture around 55.0 percent. This level of consolidation suggests a market where scale, brand equity, and distribution reach matter significantly. Yet concentration also creates friction for mid-tier and regional manufacturers that must differentiate without competing purely on volume. The industry is not fragmented in a way that allows easy entry. It rewards producers that can combine reliable capacity, specification flexibility, and application-specific engineering. Firms that remain positioned as generic commodity suppliers face a narrowing path to sustainable margins.
Key Drivers Reshaping Market Dynamics
Technological Advancement and Material Innovation
Product engineering has moved from a secondary concern to a core competitive lever. Grating manufacturers are increasingly differentiating through fabrication precision, load-specific designs, and surface treatments that extend service life in demanding environments. Pressed and electro-forged gratings, for example, allow tighter tolerances and more consistent anti-slip performance, which matters in walkway and platform applications where safety and durability intersect. Manufacturers that integrate custom fabrication into their core operations are better positioned to serve industrial customers with non-standard dimensions, specialized coatings, or elevated corrosion resistance requirements. This shift toward engineered solutions raises the barrier to entry and rewards capability depth over pure volume production.
In parallel, the industry is seeing gradual adoption of improved surface refinement and finishing processes. Pickling and controlled surface treatment are becoming more relevant for stainless and specialized carbon steel applications where appearance, cleanliness, and long-term corrosion control influence procurement decisions. These technical upgrades are not cosmetic. They translate into lower maintenance intervals, better compliance with hygiene or environmental specifications, and stronger positioning in applications where downtime is costly. The broader implication is that value in the steel grating market is migrating toward specification accuracy, finish quality, and application engineering, rather than remaining anchored solely to base metal weight and standard profiles.
Policy Frameworks and Trade Oversight
Policy and trade dynamics are actively shaping cost structures and sourcing decisions. The May 2026 decision by the United States International Trade Commission to open five-year reviews for Chinese steel grating imports underscores the continued scrutiny of cross-border competition. For domestic producers, this environment can reinforce the case for localized capacity and established supply relationships. For buyers and distributors, it introduces both risk and opportunity, depending on how procurement portfolios are structured. Where reliance on low-cost imports has been a primary margin strategy, renewed duty exposure can compress flexibility and force rapid renegotiation of supply terms.
Environmental regulation is also influencing upstream conditions. The finalization of amendments to National Emission Standards for Hazardous Air Pollutants related to taconite iron ore processing in March 2024 affects the feedstock environment for steel production. While the direct impact reaches further up the value chain, the downstream consequence is a regulatory landscape that can influence iron ore processing economics and, indirectly, the stability of input costs for steel-intensive products. Producers and procurement teams that monitor these regulatory milestones can anticipate shifts in feedstock cost structures earlier and adjust hedging, inventory, or supplier diversification strategies accordingly.
Demand-Side Evolution in Industrial and Infrastructure Applications
Demand patterns are shifting as end users prioritize safety, asset longevity, and functional integration. Walkways remain a significant application area, reflecting ongoing needs in industrial facilities, utilities, and commercial infrastructure where safe pedestrian access must be maintained under heavy use or harsh conditions. Platforms represent another substantial demand center, particularly in processing plants, energy operations, and manufacturing environments where equipment access, inspection routes, and worker safety zones must be structurally reliable. Stair treads continue to draw consistent demand due to their dual role in functionality and code-driven safety requirements.
Beyond these core uses, security fencing, drainage covers, and trench covers illustrate how steel grating is increasingly specified as part of broader infrastructure and site-management solutions. Procurement teams are no longer buying grating simply as an isolated metal component. They are integrating it into facility design, drainage planning, perimeter security, and load-bearing access systems. This application-level thinking increases the importance of product consistency, lead-time reliability, and technical support. Buyers are more likely to consolidate suppliers that can deliver across multiple application needs, which in turn rewards manufacturers with broader catalogs and stronger service capabilities.
Supply Chain Cost Architecture and Operational Pressure
The cost environment is being reshaped by more than commodity price movement alone. Labor costs and freight expenses continue to rise, adding pressure that extends well beyond initial steel price fluctuations. This broader cost architecture means that manufacturers must manage a wider set of margin variables simultaneously. Efficient production scheduling, regional distribution logic, and freight-sensitive order optimization are becoming part of the competitive formula. Producers that can align capacity with demand geography, reduce unnecessary handling, and maintain consistent order fulfillment gain an advantage that is not always visible in raw material benchmarks alone.
At the same time, carbon steel price volatility remains a persistent feature of the landscape. The impact is felt not only in direct input costs but also in the predictability of quoting, contracting, and inventory planning. In a market where customers increasingly value reliability and specification accuracy, the ability to manage price variability without sacrificing responsiveness is a meaningful operational capability. This is one reason why strategic sourcing, forward purchasing discipline, and transparent price communication are becoming central topics in buyer-supplier negotiations.
Competitive Positioning and Market Structure
The competitive landscape is anchored by manufacturers that combine production scale, application breadth, and regional footprint. Nucor Corporation operates steel bar grating through its Vulcraft and Verco divisions, with annual capacity around 50,000 tons and a product range that spans standard, heavy-duty, and custom-fabricated offerings. This positions the company within a broader structural steel ecosystem where grating is integrated with complementary metal products and distributed through established industrial channels. Its scale and divisional integration provide a strong foundation for serving large-volume and specification-driven buyers.
IKG has built a recognized position in pressure-locked bar grating and safety flooring, supported by more than 100 years of expertise across the United States and Mexico. Its full product line includes pressure-locked and anti-slip solutions, which align closely with demand in access infrastructure and safety-critical applications. Ohio Gratings stands out as the largest privately-owned industrial and commercial grating provider in the United States, with specialization in design, manufacturing, and custom fabrication using carbon steel, stainless steel, and aluminum. That combination of private ownership and broad material capability allows a high degree of flexibility in custom work and customer-specific engineering.
AMICO continues to emphasize domestically produced bar grating for industrial applications, expanding its range to include common bar grating items. This focus on U.S.-based production appeals to buyers prioritizing supply continuity, domestic sourcing expectations, and shorter lead times for standard products. On the international side, JK TECHNIC in France manufactures pressed gratings, electro-forged grating, and solutions for stair treads, platforms, and industrial applications, while Meiser in Germany focuses on high-grade products and surface refinement, including pickling, and maintains a U.S. subsidiary through Meiser Gratings Inc. These European manufacturers illustrate how specialized finishing capability and engineered product lines can support cross-border positioning, particularly where surface quality and specification precision are valued.
A defining recent development is the February 2026 acquisition of IKG by a joint venture of Meiser and Dutco from KPS Capital Partners. The transaction is notable because it combines brands and capacity to form what is described as the world's largest grating manufacturer. This kind of consolidation signals a market trajectory toward greater scale integration, shared technical resources, and broader geographic coverage. For the competitive field, it raises the strategic stakes around capacity alignment, brand portfolio strength, and the ability to serve multi-region demand without losing application-specific expertise. Consolidation of this nature can improve purchasing leverage and production efficiency, but it also places pressure on remaining independent players to clarify their differentiation, whether through custom fabrication speed, regional service density, or niche material expertise.
Market evolution is therefore shaped by both integration and specialization. Large-scale combinations can capture efficiencies and widen distribution reach, while privately-held and regionally anchored manufacturers can compete by offering faster custom turnaround, closer customer collaboration, and material-specific proficiency. New entrants face a challenging environment given the concentrated revenue structure and the importance of established production capability. As a result, the most viable path for expansion is often through targeted capability building, strategic partnerships, or acquisition of specialized assets rather than attempting to compete purely on price in standard product categories.
PW Consulting Chemical & Energy Research Center
Forward Outlook and Emerging Opportunities
Consolidation as a Strategic Accelerator
Over the next three to five years, further consolidation is likely to remain a central theme, particularly where combined capacity can strengthen supply reliability and broaden application coverage. The recent move to unite major brands and production resources illustrates how scale can be leveraged not only for cost efficiency but also for a wider product and service footprint. For customers, this can translate into simpler sourcing across multiple grating types and faster access to engineered solutions. For competitors, the strategic response will involve deciding whether to pursue scale through partnership or acquisition, or to double down on differentiation through customization, regional responsiveness, and specialized material performance.
Regulatory Continuity and Sourcing Realignment
Trade oversight and environmental regulation are expected to continue influencing sourcing strategies. The review of duties on Chinese steel grating and the broader regulatory environment around steel production feedstock suggest that supply chain design will remain dynamic. In practical terms, this creates opportunities for producers with stable domestic or near-shore capacity, as well as for procurement teams that build flexibility into supplier portfolios. Companies that preempt regulatory review cycles by diversifying sources, strengthening quality documentation, and aligning lead times with trade uncertainty will be better positioned to maintain continuity when policy conditions shift.
Engineered, Application-Specific Solutions as a Growth Axis
A third forward trend is the increasing premium on application-tailored grating products. As end users integrate grating into safety systems, drainage infrastructure, security setups, and industrial access platforms, the specification process becomes more nuanced. This favors manufacturers that can support custom dimensions, refined surface finishes, anti-slip performance, and consistent load-bearing characteristics. The commercial opportunity lies in moving up the value chain from commodity supply toward solution provision. Suppliers that invest in engineering support, responsive fabrication, and application knowledge can capture higher-margin work and build stickier customer relationships.
Steel Roofing Market
These trends also carry risk. Over-reliance on any single region, feedstock channel, or pricing model can become exposed if trade conditions change, raw material volatility intensifies, or labor and freight costs continue to rise. Additionally, if consolidation proceeds too aggressively without preserving local service quality or customization capacity, some customers may seek alternatives that can offer more direct engagement and faster adaptation to project-specific requirements. The balance between scale and responsiveness will therefore remain a critical strategic tension.
Strategic Actions for Decision-Makers
For manufacturers, the priority is to strengthen the operational and technical foundations that support margin resilience and customer retention. This includes tightening cost pass-through mechanisms, investing in custom fabrication capability, and clarifying material specialization where it creates genuine differentiation. Producers should also evaluate whether their distribution and service models align with application-driven buying behavior. Where customers increasingly seek integrated solutions across walkways, platforms, stair treads, and covers, manufacturers that can respond with consistent quality and specification support will have a stronger competitive position. In an environment shaped by consolidation, clearly defined differentiation is not optional. It is the basis for defending share without engaging in unsustainable price competition.
For investors, the market presents a landscape where scale, integration, and application capability matter more than ever. The recent formation of a combined global-scale manufacturer highlights the value created through strategic consolidation, but it also underscores the need to assess whether scale translates into durable margins, better customer coverage, and operational flexibility. Investment decisions should account for exposure to trade review cycles, raw material volatility, and the extent to which a company's portfolio is tied to standard commodity products versus engineered, specification-sensitive solutions. Companies that can demonstrate both capacity reliability and the ability to serve higher-value application segments are better positioned for long-term relevance.
For procurement and supply chain leaders, the key is to move beyond price-only evaluation and build sourcing strategies that account for regulatory continuity, lead-time stability, and specification performance. Diversifying suppliers across regions and product types can reduce vulnerability to duty reviews or feedstock disruptions. At the same time, developing clearer technical requirements around load capacity, surface treatment, anti-slip performance, and corrosion resistance can improve long-term total cost outcomes by reducing maintenance, downtime, and replacement frequency. Procurement teams that engage earlier with manufacturers on application needs and lead-time planning are more likely to secure consistent supply and avoid reactive purchasing when market conditions tighten.
Structural Steel Market
Across all of these perspectives, the strategic value of detailed, segment-level intelligence is clear. Broad market direction provides context, but the decisions that shape outcomes sit in the specifics: how demand is distributed across applications, which material types are gaining or losing relative share, where regional capacity is expanding or constrained, and how competitive consolidation is altering supply dynamics. A more comprehensive view of these elements supports sharper planning, more disciplined sourcing, and better-timed investment choices. For organizations that need granular segment data, competitive tracking, and tailored scenario analysis, the full research report offers a deeper breakdown of market structure and forward options.
For detailed analysis of this topic, please visit the official page: Steel Grating Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Fiber Cement Market 2026: Asia Pacific's 9.79B Demand Reshapes Growth Beyond 4.08% CAGR
By PW Consulting, 2026-09-21
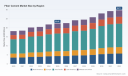
Strategic Trends and Commercial Opportunities in the Fiber Cement Market: A 2032 Outlook
The global fiber cement market has established itself as a cornerstone of modern construction materials, driven by the demand for durable, fire-resistant, and low-maintenance building envelopes. As of 2025, the market is valued at 22.45 billion USD, reflecting steady growth from 18.17 billion USD in 2020. This trajectory indicates a compound annual growth rate of approximately 4.08% through 2032, signaling a mature yet expanding sector. The forecast period from 2026 to 2032 suggests continued momentum, with projected revenues reaching nearly 29.71 billion USD by the end of the decade. This growth is not uniform; it is shaped by regional dynamics, technological advancements, and shifting regulatory landscapes. For executives and investors, understanding the underlying forces behind these figures is critical to capitalizing on emerging opportunities while mitigating structural risks.
Fiber Cement Board Market
Market Resilience Amidst Structural Headwinds
Despite the positive growth trajectory, the industry faces significant challenges that demand strategic attention. The market is characterized by high concentration, with the top three players commanding 60% of the revenue and the top five holding 70%. Such consolidation creates barriers for new entrants and places pressure on mid-tier manufacturers to differentiate or consolidate. Additionally, the production of fiber cement involves fibrous silicate minerals, which have come under increased regulatory scrutiny. In 2025, the United States Environmental Protection Agency issued instructions on safe use and exposure during manufacturing, while the government of British Columbia proposed additional safety measures for plants handling these materials. These regulatory shifts introduce compliance costs and operational complexities that can erode margins if not managed proactively. Furthermore, raw material price fluctuations for cement and cellulose have raised production costs, compounding the pressure from rising labor expenses in high-cost regions.
The Inflection Point: Compliance vs. Innovation
The industry is currently at an inflection point where regulatory compliance and technological innovation intersect. Manufacturers must navigate the dual challenge of adhering to stricter safety protocols while simultaneously investing in product enhancements that justify premium pricing. The balance between cost efficiency and safety standards is becoming a key differentiator. Companies that treat compliance as a mere obligation risk falling behind, whereas those that integrate safety into their operational ethos can leverage it as a competitive advantage. This dynamic is reshaping the competitive landscape, favoring firms with robust R&D capabilities and agile supply chains.
Cement Boards Market
Key Drivers Shaping Market Evolution
Several core factors are propelling the fiber cement market forward, creating a complex environment where strategic agility is paramount.
Technological Innovation and Product Differentiation
Innovation remains a primary catalyst for growth. Manufacturers are continuously expanding their portfolios to meet diverse architectural and performance needs. For instance, in February 2025, James Hardie Building Products Inc. unveiled new and expanded Hardie® products, including Artisan Trim, at the NAHB International Builders' Show. This move highlights the industry's focus on aesthetic versatility and customization, allowing fiber cement to compete more effectively with traditional materials like wood and vinyl. Such product unveilings are not merely incremental; they represent a strategic push to capture higher-margin segments within the siding and trim categories. As consumers and builders increasingly demand materials that offer both durability and design flexibility, companies that lead in product innovation are well-positioned to capture market share.
Regulatory Environment and Standardization
Regulatory developments are fundamentally altering the market's operational framework. In October 2025, ICC-ES proposed new criteria for fibre-cement siding complying with ASTM C1186 or ISO 8336 in both combustible and noncombustible construction. This standardization effort aims to clarify performance expectations and facilitate broader adoption in construction projects where fire safety is paramount. Simultaneously, environmental regulations regarding fibrous silicate minerals are tightening. The EPA's guidelines on safe use and exposure, along with provincial measures in British Columbia, signal a global trend toward stricter occupational and environmental health standards. While these regulations increase compliance burdens, they also raise the barrier to entry, potentially consolidating the market further around established players with the resources to manage complex regulatory requirements. Standardization can also open new application avenues, particularly in commercial and multi-family residential sectors where code compliance is a critical decision factor.
Demand-Side Shifts and Cost Pressures
On the demand side, the construction industry's preference for low-maintenance and long-lasting materials continues to drive adoption. Fiber cement's resistance to rot, pests, and fire aligns with the growing emphasis on sustainable and resilient building practices. However, cost structures are evolving. Raw material price volatility for cement and cellulose directly impacts production economics, forcing manufacturers to optimize supply chains or pass costs to customers. Concurrently, the cost of living in high-cost states drives up both labor and material costs for fiber cement siding projects, which can dampen demand in price-sensitive segments. This economic pressure is prompting buyers to evaluate total cost of ownership rather than upfront prices, favoring materials that reduce lifecycle maintenance expenses. Manufacturers must therefore communicate value propositions that extend beyond unit price, emphasizing durability and energy efficiency benefits.
Supply Chain Dynamics and Regional Concentration
Supply chain resilience has become a focal point, particularly given the geographic distribution of production and consumption. Asia Pacific represents the largest revenue contributor, reflecting rapid urbanization and infrastructure development in the region. North America follows as a significant market, driven by residential renovation and new construction activity. The concentration of revenue in these regions underscores the importance of localized supply chains and distribution networks. Disruptions in raw material sourcing or logistics can have outsized impacts, making diversification and strategic partnerships essential. Companies are increasingly investing in regional manufacturing capabilities to reduce lead times and mitigate currency or tariff risks. This localization trend also supports faster response to regional building codes and consumer preferences.
Competitive Landscape and Leadership Strategies
The fiber cement market is defined by a mix of global giants and regional specialists, each pursuing distinct strategies to secure their position.
Strategic Positioning of Leading Players
James Hardie Industries PLC, headquartered in Ireland, maintains a strong focus on Hardie® fiber cement siding and backer boards, leveraging its brand recognition and extensive distribution network in North America. The company's recent activities, such as the three-year exclusive agreement with Davidson Homes announced in May 2025, illustrate a strategy of deepening partnerships with key builders to secure volume and market presence. This approach not only guarantees supply volume for Hardie® siding and trim products but also embeds the brand into the builder's product specifications, creating switching costs for competitors.
ETEX Group, based in Belgium, specializes in fiber cement boards and sheets, catering to a broad range of construction applications. Their strategy emphasizes product versatility and technical performance, positioning them as a reliable supplier for both residential and commercial projects. Saint-Gobain, a France-based multinational, offers fiber cement products for construction applications, benefiting from its vast resources and cross-industry synergies. The company's scale allows it to invest in sustainability initiatives and global distribution, appealing to large-scale developers and institutional buyers who prioritize supplier stability and comprehensive product lines.
Nichiha Corporation from Japan focuses on high-performance fiber cement panels and siding, leveraging technological expertise to deliver products with superior durability and aesthetic qualities. This focus on high-performance segments allows them to command premium pricing in markets that value advanced material properties. Cembrit Holding A/S, headquartered in Denmark, provides fiber cement siding and exterior products, with a strong presence in European markets where aesthetic preferences and regulatory standards differ from those in North America.
In the United States, companies like Allura USA and American Fiber Cement Corporation offer fiber cement siding products and boards, competing on regional availability and customer service. Allura USA's focus on fiber cement siding products positions it as a direct competitor in the residential siding segment, where brand loyalty and installer networks play crucial roles. American Fiber Cement Corporation's offering of fiber cement boards and sheets addresses both siding and industrial applications, diversifying its revenue streams.
Elementia Materials from Mexico supplies fiber cement products for construction, capitalizing on its proximity to the North American market and cost advantages. Everest Industries Limited, based in India, produces fiber cement boards, tapping into the growing demand for affordable yet durable building materials in emerging economies. CSR Limited in Australia provides fiber cement products, serving the Asia Pacific region with a focus on local market requirements. Plycem Corporation and Swisspearl Group, both US and Switzerland-based respectively, offer fiber cement siding, boards, and cladding, emphasizing quality and design in their respective markets.
PW Consulting
Competitive Dynamics and Market Evolution
The competitive landscape is evolving through a combination of integration, differentiation, and selective entry. The high market concentration suggests that mergers and acquisitions may continue as larger players seek to expand their geographic reach or product portfolios. However, niche players are finding opportunities by specializing in specific applications, such as high-performance panels or decorative trim, where they can build strong brand identities. New entrants face significant hurdles due to regulatory barriers and the capital intensity of manufacturing, but strategic partnerships or acquisitions of smaller brands can provide a pathway to market. The trend toward exclusive distribution agreements, as seen with James Hardie and Davidson Homes, indicates a shift toward securing dedicated channel partnerships to ensure stable demand and reduce competitive pressure in key accounts.
Future Trends and Commercial Opportunities (2026-2032)
Looking ahead, several trends will shape the fiber cement market, presenting both opportunities and risks for stakeholders.
Trend 1: Consolidation of Standards and Expansion into New Applications
As regulatory bodies like ICC-ES finalize criteria for fibre-cement siding, the market is likely to see a harmonization of standards that facilitates broader adoption in commercial and multi-family construction. This trend opens opportunities for manufacturers to develop products that exceed new performance benchmarks, positioning them as preferred choices for code-compliant projects. The clarification of combustible and noncombustible construction usage can unlock new revenue streams, particularly in regions where fire safety regulations have previously limited material choices. Companies that proactively align their product development with these standards can gain first-mover advantage in emerging application segments.
Trend 2: Supply Chain Localization and Cost Optimization
Continued raw material volatility and labor cost pressures will drive further localization of supply chains. Manufacturers will increasingly invest in regional production facilities to reduce logistics costs and respond faster to local demand fluctuations. This trend favors companies with the capital to expand capacity or form joint ventures with local partners. For investors, regions with growing construction activity and favorable cost structures, such as parts of Asia Pacific and Latin America, may offer higher growth potential. However, localization also requires navigating diverse regulatory environments and building local expertise, which can be resource-intensive. Opportunities exist for firms that can balance global scale with local agility, leveraging regional hubs to serve nearby markets efficiently.
Trend 3: Sustainability and Lifecycle Value as Purchasing Drivers
Sustainability is becoming a more prominent factor in material selection, driven by both regulatory requirements and consumer preference for eco-friendly buildings. Fiber cement's durability and resistance to environmental degradation align with lifecycle assessment criteria, potentially giving it an edge over materials with shorter lifespans or higher maintenance needs. Manufacturers that can provide transparent data on environmental impact, recycling potential, and energy efficiency benefits will be better positioned to capture projects with green building certifications. This trend also creates opportunities for innovation in formulations that reduce the use of regulated materials or improve recyclability. However, the risk lies in greenwashing accusations or failure to substantiate claims, which can damage brand reputation. Stakeholders must ensure that sustainability messaging is backed by verifiable data and third-party certifications.
Actionable Insights for Decision Makers
For executives, investors, and procurement professionals, navigating the fiber cement market requires a clear understanding of where to focus efforts and resources.
For Manufacturers and Producers
Prioritize innovation in product lines that address emerging aesthetic and performance demands, such as specialized trim and high-performance panels. Invest in compliance infrastructure to navigate evolving regulations regarding fibrous silicate minerals and product standards, turning these requirements into a competitive moat. Explore strategic partnerships or exclusive agreements with key builders and distributors to secure demand and reduce channel conflict. Additionally, evaluate supply chain resilience by diversifying raw material sources and considering regional production investments to mitigate cost volatility and logistics risks. Building a robust installer and contractor network can also enhance market penetration, as these groups influence product specification at the project level.
For Investors and Capital Allocators
Focus on companies with strong market positions, high concentration advantages, and the capability to invest in R&D and compliance. The market's growth trajectory suggests steady returns, but selectivity is crucial given the concentration and regulatory risks. Look for firms that demonstrate adaptability to regional demand shifts and have strategies to manage raw material and labor cost pressures. Consider the potential of consolidation plays, where acquiring regional players can accelerate market entry or product diversification. Due diligence should include a thorough assessment of regulatory exposure, supply chain dependencies, and the sustainability of competitive advantages in a market where barriers to entry are rising.
For Procurement and Construction Decision Makers
Evaluate fiber cement products based on total cost of ownership, including durability, maintenance requirements, and compliance with local building codes. Engage with suppliers that offer transparent information on product performance, safety standards, and environmental impact. Consider the reputational and operational risks associated with supply chain disruptions; diversifying suppliers or selecting manufacturers with localized production can mitigate these risks. Stay informed about evolving standards, such as the proposed ICC-ES criteria, to ensure that selected materials meet current and future code requirements. Building relationships with manufacturers that provide technical support and installer training can also reduce installation errors and improve project outcomes.
Accessing Detailed Intelligence for Strategic Advantage
The fiber cement market presents a complex array of opportunities and challenges that require granular data and tailored analysis to navigate effectively. While macroeconomic trends and competitive dynamics provide a high-level view, the specific nuances of regional demand, segment performance, and company-level strategies are essential for making informed decisions. Detailed segmentation data, including breakdowns by region, type, and application, can reveal hidden growth pockets and inform targeted market entry or expansion plans. Furthermore, customized insights into supply chain dynamics, regulatory timelines, and competitor benchmarking can help organizations anticipate shifts and allocate resources with precision. For those seeking to deepen their understanding and refine their strategic planning, accessing comprehensive research reports with granular segmentation and proprietary analysis is a valuable step toward securing a competitive edge in this evolving market.
For detailed analysis of this topic, please visit the official page: Fiber Cement Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Electric Toothbrush Market: How the 6.98% CAGR and Asia Pacific Surge Redefine Growth Beyond 2032
By PW Consulting, 2026-09-21
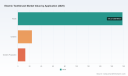
Strategic Trends and Commercial Opportunities in the Electric Toothbrush Market
Market Overview and Core Challenges
The global electric toothbrush market has demonstrated consistent expansion over the past half-decade, reaching an estimated 215.0 million USD in 2025. Historical growth from 163.15 million USD in 2020 reflects a sustained shift in consumer oral care preferences, while the projected trajectory through 2032 points toward a market approaching 344.8 million USD. This expansion is underpinned by a compound annual growth rate of approximately 6.98 percent, signaling steady but not explosive momentum. The market structure remains relatively fragmented, with the top three players capturing less than a quarter of total revenue and the top five holding just over a quarter. Such concentration levels indicate that no single entity dominates the value chain, leaving meaningful room for differentiation and strategic positioning.
Electric Dental Handpieces Market
Despite the positive trajectory, the industry faces several structural challenges that will shape competitive outcomes over the next cycle. First, the transition from basic cleaning functionality to connected, data-driven oral care is raising the bar for product differentiation. Consumers increasingly expect seamless app integration, personalized brushing feedback, and durable hardware, which compresses margins for generic manufacturers and rewards companies with robust software ecosystems. Second, regulatory complexity continues to constrain speed-to-market. In the United States, electric toothbrushes are classified as Class II medical devices, requiring 510(k) premarket notification clearance. Compliance with ISO 19452:2022 for performance testing, alongside material and chemical standards tied to FDA 21 CFR Part 177 and biocompatibility requirements, adds layers of validation that smaller entrants must navigate carefully. Third, cost structures are bifurcating. Entry-level units now carry manufacturing costs in the range of 6 to 11 USD, while ultra-premium smart devices can reach 31 to 55 USD per unit. This spread forces companies to make deliberate portfolio choices: compete on volume and accessibility, or invest in premium features and validation that justify higher price points.
Key Drivers of Market Evolution
Technological Innovation and Intelligent Oral Care
The most consequential shift in the electric toothbrush space is the migration from mechanical cleaning to intelligent, feedback-enabled hygiene. Sonic technology continues to lead share of attention, but the real value creation lies in how companies embed sensors, pressure monitoring, and app-based coaching into the user experience. Recent product launches illustrate this direction. In March 2026, Royal Philips N.V. introduced two new Philips Sonicare ranges built around next-generation sonic technology, fluid action cleaning, pressure sensors, and app connectivity, signaling a continued emphasis on clinical-style cleaning paired with digital engagement. Earlier, in February 2026, quip expanded its Ultra family with the Ultra Lite Sonic Electric Toothbrush, featuring EasyClick brush pods, a pressure sensor, and extended battery life. The move highlights how design simplicity and modular replacement systems can lower friction for users migrating from manual brushes. In January 2025, Procter & Gamble Co. launched the Oral-B iO2, an oscillating-rotation model positioned for users making the easiest switch from manual brushing, underscoring the importance of onboarding and ease of use in driving conversion.
These developments point to a broader pattern: hardware excellence is becoming table stakes, while differentiation is increasingly driven by software, data, and user journey design. Companies that can translate brushing data into actionable habits, reduce replacement friction, and maintain clinically credible cleaning claims are better positioned to command loyalty and justify premium pricing.
Regulatory and Standards Environment
Regulatory expectations are tightening around performance validation and material safety. Powered toothbrushes must comply with ISO 19452:2022 for test methods that measure performance, and manufacturers must ensure that brush heads and materials meet FDA regulations for medical devices, including biocompatibility testing and FDA 21 CFR Part 177 for food-contact and medical-grade materials. These requirements do not merely add compliance overhead; they shape product architecture, supplier selection, and time-to-market. Firms that standardize testing protocols early, invest in material qualification, and document validation trails can reduce launch risk and build trust with dental professionals and retail partners. The regulatory backdrop also creates an implicit moat: brands that can demonstrate consistent compliance and clinical-style performance claims gain credibility that generic alternatives struggle to replicate.
Consumer Behavior and Demand-Side Shifts
Demand-side dynamics are being reshaped by three interrelated forces. First, oral care is increasingly viewed through a preventive health lens, with consumers and dental professionals alike emphasizing plaque removal, gum health, and consistent technique. This framing supports repeat purchases of replacement heads and encourages adoption among users who previously relied on manual brushes. Second, subscription and refill models are expanding the commercial relationship beyond the initial hardware sale. Modular pod systems, predictable replacement cycles, and bundled accessories create recurring revenue streams and deepen brand touchpoints. Third, eligibility dynamics are evolving. There is growing industry attention around the potential expansion of FSA/HSA eligibility for oral care products, including electric toothbrushes, which would offer consumers additional tax-advantaged spending options and could lower effective purchase barriers for certain segments. Even before formal changes, the conversation signals that oral care devices are increasingly positioned alongside health-related expenditures, reinforcing premiumization and repeat usage narratives.
Cost Structures and Supply Chain Realities
Manufacturing economics are pressuring both ends of the portfolio. At the entry level, cost discipline is essential to maintain acceptable margins while competing on accessibility. At the premium end, the cost of sensors, batteries, app infrastructure, and certification can escalate quickly, requiring careful feature prioritization. The supply base reflects this tension: a mix of established consumer goods manufacturers, dental-focused innovators, and specialized OEM/ODM partners in Shenzhen and surrounding regions offers customization, ISO 13485 and FDA-aligned certifications, and volume flexibility. This ecosystem enables faster iteration and private-label options, but it also raises quality assurance and brand consistency considerations. Companies that invest in supplier qualification, standardized testing, and clear design-to-manufacturing handoffs can reduce variability and protect brand integrity as they scale.
Competitive Landscape and Leading Strategies
The competitive field combines large consumer goods portfolios, dental-adjacent specialists, and a growing cohort of Chinese OEMs and smart-device innovators. Royal Philips N.V. continues to anchor its position around Philips Sonicare, leveraging next-generation sonic technology, fluid action cleaning, pressure sensing, and app connectivity to frame the category around clinical-style cleaning and guided habits. Procter & Gamble Co. competes through Oral-B's oscillating-rotation heritage, with the iO2 launch emphasizing the easiest transition from manual brushing, a strategic focus on reducing adoption friction. Colgate-Palmolive Company positions its electric toothbrushes around oscillating-rotation technology for plaque and stain removal, aligning with its broader oral care distribution strengths. Water Pik, Inc. differentiates by combining sonic oscillation with water flossing capabilities, appealing to users seeking a more comprehensive hygiene routine in a single device.
Smaller and mid-tier players are carving out niches through design, material choice, and smart features. Foreo emphasizes sonic technology with medical-grade silicone bristles for gentle, effective cleaning, targeting users who prioritize soft-tissue comfort. quip focuses on minimalist design, EasyClick brush pods, pressure sensors, and long battery life, lowering the barriers to consistent use. Oclean Technology Co., Ltd. pursues AI coaching, app connectivity, and high-performance sonic oscillation to deliver professional-level feedback, aligning with the intelligence trend. Broxo S.A. maintains a clinical focus on plaque removal and gum health, while Panasonic Corporation offers user-friendly sonic designs that balance performance and accessibility. On the supply side, a network of Shenzhen- and Ningbo-based manufacturers, including Relish Tech, Auxbon, Shenzhen Libai Technology, and several Ningbo and Yueqing producers, provides OEM/ODM capacity with ISO 13485 and FDA-aligned certifications, enabling global brands to iterate quickly and localize offerings.
The landscape is evolving along two parallel tracks. On one hand, consolidation pressure is building as larger players seek to strengthen digital engagement, repeat-purchase models, and clinical credibility. On the other hand, fragmentation persists at the smart-device and OEM level, where rapid iteration, modular designs, and regional manufacturing flexibility allow new entrants to test differentiated value propositions. The strategic implication is clear: scale alone is insufficient. Winning positions will combine credible cleaning performance, compliant materials and testing, a compelling user journey, and a commercial model that captures recurring value after the initial sale.
Future Trends and Commercial Opportunities
Intelligent, Habit-Forming Oral Care
Over the next three to five years, the market is likely to reward products that translate brushing into measurable, coachable habits. Expect tighter integration between hardware sensors and app-based feedback, more refined pressure and coverage metrics, and design choices that reduce friction in replacement and charging. The commercial opportunity lies in pairing hardware with services: subscription refills, personalized recommendations, and dental-professional-aligned guidance that reinforce consistent use. Brands that can demonstrate credible performance while making good habits effortless will be better positioned to retain users and defend premium pricing. The risk is feature creep without corresponding value; overly complex apps or unreliable sensors can erode trust and increase support costs.
Premiumization Paired with Accessibility Tiers
The market is moving toward a dual-structure portfolio strategy. Premium smart devices will continue to target users willing to pay for connectivity, coaching, and refined materials, while entry-level and mid-tier models will compete on reliability, ease of use, and affordability. This bifurcation creates opportunities for tiered branding, modular feature sets, and channel-specific assortments. Manufacturers can use OEM/ODM partnerships to scale distinct tiers efficiently, provided they maintain quality and compliance discipline across the range. The key uncertainty is how quickly reimbursement and tax-advantaged spending dynamics evolve; if FSA/HSA eligibility broadens, it could accelerate adoption in certain segments and shift price sensitivity, while a slower trajectory would keep volume growth dependent on out-of-pocket conversion.
Compliance and Clinical Credibility as Differentiators
As the category matures, regulatory and standards compliance will increasingly function as a differentiator rather than a hurdle. Manufacturers that standardize ISO 19452:2022 testing, maintain rigorous material and biocompatibility documentation, and align brush head materials with FDA expectations will reduce launch risk and strengthen retailer and professional confidence. The opportunity is to use compliance and validated performance as narrative anchors in marketing, retail merchandising, and dental-channel engagement. The downside risk is complacency: incremental changes in material regulations or testing expectations can disrupt product lines if qualification processes are not proactive and well-documented.
Strategic Implications for Decision-Makers
For Manufacturers and Brand Owners
Build a portfolio that explicitly separates accessibility from intelligence. Use modular hardware and replaceable pod systems to reduce long-term friction, and invest in app and sensor design that delivers consistent, understandable feedback. Prioritize compliance infrastructure early, including ISO 19452:2022 testing and material qualification aligned with FDA expectations, so that performance claims and launch timelines remain credible. Evaluate OEM/ODM partners for quality systems, certification coverage, and design-to-production consistency, and use regional manufacturing flexibility to scale tiers without compromising brand standards.
For Investors
Focus on business models that capture value beyond the initial hardware sale. Recurring revenue from refills, subscription pods, and accessories can improve durability of margins and reduce reliance on cyclical replacement cycles. Assess whether a company's differentiation rests on defensible features—credible cleaning performance, compliant materials, and engaging software—rather than transient marketing claims. Pay attention to regulatory readiness and supplier qualification, as these factors increasingly influence launch speed and retail access. Monitor the reimbursement conversation as a potential catalyst that could shift effective price sensitivity in select markets.
PW Consulting
For Procurement and Channel Partners
Prioritize suppliers with documented compliance trails, standardized performance testing, and clear material specifications. Consistency across batches and regions matters as much as unit cost, particularly for premium SKUs where brand trust and professional recommendation drive repeat purchases. Evaluate replacement-system design and battery life as practical determinants of customer satisfaction and return rates. Where possible, structure contracting to ensure quality assurance, certification continuity, and transparent testing documentation, reducing the risk of downstream compliance or performance issues.
The electric toothbrush market is entering a phase where growth is increasingly defined by how well companies convert hardware capability into sustained user behavior, credible performance, and compliant, repeatable operations. For decision-makers seeking deeper segmentation data, pricing dynamics, and customized go-to-market guidance, the full PW Consulting research report provides the granular detail needed to translate these trends into specific commercial moves.
Power Toothbrush Market
For detailed analysis of this topic, please visit the official page: Electric Toothbrush Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
POE Market CAGR: The 7.6% Growth Story Reshaping Automotive and Packaging Demand
By PW Consulting, 2026-09-21
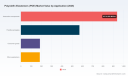
Polyolefin Elastomers (POE) Market: Strategic Shifts and Profitable Pathways Through 2032
The polyolefin elastomers (POE) sector is entering a phase of accelerated transformation, driven by a convergence of material science breakthroughs, shifting end-use requirements, and deliberate capacity strategies. Market size has expanded from 1,200.0 million USD in 2020 to 1,880.0 million USD in 2025, and the trajectory extends through 2032, reaching 3,112.0 million USD. The compound annual growth rate of 7.6 percent over the 2026–2032 forecast period underscores a market that is no longer growing purely on volume expansion, but increasingly on value capture, application migration, and regional realignment.
PW Consulting
A market expanding at this pace does not simply reward incremental improvements. It rewards organizations that can anticipate how performance requirements, regulatory expectations, and supply chain architecture will evolve together. POE has moved from a niche additive and specialty modifier into a core enabler for lightweighting, flexible barrier systems, durable consumer products, and increasingly, advanced electronics and renewable energy components. The question for executives, planners, and investors is not whether the category will grow, but where margin will concentrate and where competition will intensify.
The current landscape is defined by a high degree of concentration, with the top three players accounting for 65.0 percent of market revenue and the top five reaching 80.0 percent. This concentration suggests that leadership positions are already established, but it also signals that the next wave of growth will likely emerge through application-specific differentiation, capacity timing, and strategic consolidation rather than broad-based market sharing.
Market Snapshot and the Structural Crossroads
Over the 2020–2025 period, the category moved from 1,200.0 million USD to 1,880.0 million USD, reflecting a steady step-up in demand across automotive components, flexible packaging, consumer goods, and other applications. By 2025, the regional distribution indicates strong commercial presence across North America, Europe, Asia Pacific, Latin America, and the Middle East and Africa, with the largest revenue pools clustered in the most industrialized and automotive-intensive markets. On a type basis, polyethylene-based POE leads with 1,412.47 million USD, while polypropylene-based POE contributes 467.53 million USD, reflecting differing property profiles and end-use preferences.
This market is now at a structural crossroads. Growth is no longer a simple function of adding capacity; it depends on aligning resin design with application economics, securing feedstock stability, and navigating an increasingly complex sustainability and compliance environment. Three challenges stand out as particularly consequential.
The first is the tension between volume expansion and differentiation. As new capacity comes online and regional supply grows, commodity pressure can compress pricing for undifferentiated grades. The organizations that protect margin will be those that translate technical properties into measurable cost-in-use advantages, not those that compete solely on price per kilogram.
The second challenge is feedstock and input volatility. POE economics remain tightly linked to ethylene, propylene, catalyst systems, and energy costs. Capacity expansions can be undermined if feedstock arrangements, energy exposure, or plant utilization assumptions do not match the operating environment. Pricing power in the category increasingly depends on integrating supply chain resilience with product design.
The third challenge is the evolving regulatory and customer sustainability agenda. Packaging, automotive, and consumer-product buyers are placing greater weight on recyclability, material efficiency, and lower-carbon production pathways. These expectations are reshaping qualification criteria, not only environmental reporting. Materials that cannot support downstream compliance or circularity goals risk losing specification positions, even if they remain technically adequate.
Key Drivers Reshaping the POE Landscape
The market’s direction is being shaped by four reinforcing forces: material innovation, policy and regulatory momentum, demand-side substitution behavior, and supply chain reconfiguration. Each driver is altering where value is created and how quickly it can be captured.
Technological innovation continues to expand the performance ceiling. POE is increasingly chosen not simply for elasticity, but for its ability to improve toughness, sealing behavior, clarity, processability, and integration with other polymer systems. This is enabling adoption in higher-value applications where conventional elastomers or softer plastomers cannot meet combined mechanical and processing requirements. The trend is especially visible where lightweighting and part consolidation reduce total system cost, or where flexible packaging demands better barrier compatibility and strength without sacrificing seal performance.
Policy and regulatory dynamics are changing the qualification bar. In several regions, decarbonization targets, extended producer responsibility frameworks, and packaging redesign expectations are altering the base assumptions for material selection. POE grades that support downgauging, multi-material compatibility, recyclability pathways, or lower embodied carbon profiles gain a practical advantage in specification decisions. In this context, the regulatory environment is not simply a compliance cost; it is becoming a filter through which certain grades become easier to specify and others become harder to defend.
Demand-side behavior is shifting from cost-first selection to performance-in-use economics. Automotive manufacturers continue to push for weight reduction and component simplification. Packaging converters and brand owners are balancing strength, appearance, and process efficiency with sustainability commitments. Consumer goods producers are looking for materials that can improve durability and aesthetic quality while maintaining manufacturability. Across these segments, the buying logic is increasingly tied to total system outcome, including processing speed, rejection rates, downstream recyclability, and end-product performance. That shift creates room for premium and semi-premium POE grades when they solve a real application problem.
Supply chain and cost structure changes are reshaping competitive positioning. New large-scale capacity additions are expanding regional availability, particularly in Asia, while established producers refine global footprints and application portfolios. The market is also seeing targeted moves around feedstock integration, plant location strategy, and consolidation. A recent example is the preliminary merger review initiated in March 2026 by South Korea’s Ministry of Trade, Industry and Resources and the Korea Fair Trade Commission regarding Lotte Chemical’s proposed merger with Yeochun NCC. The business focus of the combined entity is expected to emphasize high value-added LDPE and POE for medical use. Even at the review stage, this development illustrates a broader strategic theme: players are repositioning capacity and product direction toward higher-margin, application-specific grades rather than generic volume.
Worldwide Propylene Based POE Market
Competitive Landscape and the Logic Behind Leading Strategies
The POE market is led by firms that combine scale, application depth, and brand recognition with increasingly targeted technology and regional strategies. The leading ecosystem includes global producers and regional specialists, each pursuing a distinct route to resilience and margin protection.
The Dow Chemical Company remains a central reference point in the market, with the largest POE production footprint and well-known product families such as ENGAGE™ and AFFINITY™ across automotive, packaging, wire and cable, and specialty applications. Its strategic strength lies in breadth of application coverage and the ability to offer multiple performance tiers that fit different buyer requirements.
ExxonMobil Corporation competes through its Vistamaxx™ line, with large-scale operations including facilities such as Baytown, Texas, and a focus on elastomers for adhesives, medical, and packaging segments. Its advantage is rooted in integrated feedstock access and the ability to scale high-performance grades for demanding use cases where consistency and property control matter.
Mitsui Chemicals, Inc. is a key international producer supplying high-performance elastomers for automotive, wire and cable, and industrial applications. Its relevance in the market comes from a clear orientation toward performance-intensive segments where customers are willing to pay for optimized material behavior.
Borealis AG has built a strong position in Europe through its Queo™ platform, with offerings spanning packaging, automotive, and medical applications. Its strength lies in regional proximity to key European converters and end users, combined with a product strategy that emphasizes innovation in polyolefin elastomer design.
LG Chem Ltd. is expanding capacity and targeting automotive and specialty elastomers for high-value applications. In a rapidly growing market, capacity expansion is strategically meaningful only when paired with grade differentiation and customer qualification. LG Chem’s focus reflects that broader logic.
SABIC, through SABIC SK Nexlene Company, produces POE with special relevance in advanced materials, including FORTIFY™ encapsulant grades for solar. This highlights an important evolution in the market: POE applications are moving beyond traditional polymer uses into areas where encapsulation, protection, and high-performance processing are critical.
Wanhua Chemical Group Co., Ltd. has moved aggressively on capacity, with a new 200,000 t/yr unit operational since 2024 and plans to expand toward 600,000 t/yr. This is a signal of how regional dynamics are shifting: large-scale capacity additions can change local supply balances quickly, but sustained advantage will depend on how effectively the producer converts volume into qualified demand.
LyondellBasell Industries N.V. operates POE production across multiple regions and supplies elastomers for wire and cable and industrial uses. Its multi-region presence helps support supply continuity and market access, an increasingly important attribute as buyers prioritize resilience alongside cost and performance.
Taken together, these players reveal a market that is simultaneously concentrated and strategically divergent. The leaders are not all competing in the same way. Some emphasize application breadth and global reach, others emphasize regional proximity and specialized grade design, and a third group is scaling capacity for high-volume markets while trying to lift value through targeted applications. This divergence is one of the most important features of the current landscape.
Consolidation is emerging as a central theme in the next stage of market evolution. Capacity rationalization, feedstock strategy alignment, and the push toward higher-value applications all favor consolidation in select chains. At the same time, differentiation is intensifying at the grade level, meaning that the market is not simply becoming more uniform; it is becoming more segmented by performance need, regional requirement, and application qualification. New entrants and capacity expansions can influence local supply, but winning position will depend on downstream relationships, technical service, and grade-level competitiveness.
PolyOlefin Elastomer (POE) Synthetic Materials Market
Forward-Looking Trends and Where Value Is Likely to Concentrate
Looking ahead across the 2026–2032 horizon, three trends appear especially likely to shape commercial outcomes.
Trend one is application migration toward higher-value specifications. POE demand will increasingly come from applications where the material is selected for system-level benefits rather than simple softness or elasticity. Automotive components will continue to be a major demand pool, but the growth logic will depend on lightweighting, part integration, and improved toughness in more complex assemblies. Flexible packaging will remain significant, with additional emphasis on strength, seal performance, and compatibility with evolving packaging formats. In parallel, specialty uses such as advanced encapsulants and performance-critical industrial applications will gain relative importance, especially where material reliability affects product lifetime or safety performance.
This trend creates commercial opportunity for producers and converters who can translate resin properties into application outcomes. It also raises the stakes for qualification: as applications become more demanding, switching costs increase, but so does the need for robust technical support and consistent supply.
Trend two is the alignment of capacity growth with value capture rather than volume alone. Capacity additions are part of the market’s growth story, but the more strategic question is where new tonnage will be directed. The most attractive positions will likely be in grades tied to higher-margin applications, feedstock-advantaged production, and regions where demand growth outpaces local supply. At the same time, regions or segments with oversupply risk will pressure undifferentiated pricing. That means capacity announcements should be read carefully: scale matters, but application selection, ramp-up quality, and customer qualification determine whether scale becomes profitable.
Trend three is regulatory and sustainability-driven specification change becoming a durable competitive factor. If packaging redesign, circularity expectations, and decarbonization pressures continue to intensify, POE grades that fit into more recyclable or more efficient material systems will have a structural advantage. This is not simply a compliance issue; it influences customer willingness to adopt, brand owner preferences, and downstream converter economics. Producers that can present credible pathways for material efficiency, recyclability compatibility, and lower-carbon production may gain access to specifications that are otherwise difficult to win.
These trends also carry risk. Feedstock volatility can erode the economics of expansion plans. Regulatory frameworks may diverge by region, creating complexity for global product rollouts. Demand shifts can alter qualification priorities faster than capacity can be adapted. And concentration in the market means that competitive reactions from leading players can quickly change pricing dynamics in key grades and regions.
Strategic Implications for Decision-Makers
For manufacturers, the immediate priority is to align grade development with application economics, not merely polymer properties. The market increasingly rewards materials that solve a downstream problem: lighter components, better seals, improved durability, improved process efficiency, or better compatibility with evolving sustainability requirements. Manufacturers should also evaluate where capacity and feedstock assumptions create durable advantage versus where they merely add volume. In a market where the top five players already account for 80.0 percent of revenue, incremental growth will often come from stealing application share through superior solution fit, not from taking broad commodity share.
For investors, the key task is to separate capacity announcements from value creation potential. Large expansions can reshape regional supply, but investment merit depends on application mix, qualification status, feedstock positioning, and the ability to protect pricing in the face of competition. The most defensible opportunities are likely in grades and applications where performance requirements are rising and switching costs are meaningful. Investors should also watch consolidation signals and regulatory developments as indicators of where the supply base is heading, since those changes can reshape competitive dynamics well before financial results fully reflect them.
For procurement and sourcing leaders, the strategic imperative is to manage total cost and qualification risk rather than focusing only on resin price. POE is increasingly specified in applications where performance inconsistency or supply disruption carries a high downstream cost. Sourcing strategies should therefore account for grade suitability, supplier technical capability, regional supply resilience, and the ability of suppliers to support evolving sustainability or compliance expectations. Where possible, long-term supply partnerships should be evaluated against the backdrop of application migration and regulatory change, since today’s qualification decisions can lock in advantages or constraints for several years.
Across all of these perspectives, timing matters. The POE market is large enough, and moving fast enough, that broad narratives can obscure important differences in grade-level demand, regional supply balance, and application qualification momentum. Decision-makers who treat POE as a single market risk missing where margins are actually being created. Those who focus on application-driven performance, feedstock and capacity strategy, and the regulatory direction of end markets are more likely to identify durable opportunities before they become crowded.
For a fuller picture of segment-level dynamics, regional demand patterns, capacity timing, and company-specific positioning, the complete study offers the deeper breakdown required for operational planning and investment decisions. In a market defined by concentrated leadership and simultaneous application divergence, detailed intelligence is often the difference between reacting to change and shaping it.
For detailed analysis of this topic, please visit the official page: Polyolefin Elastomers (POE) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Anti-Decubitus Cushions Market: How $738M in 2025 Sparks a 6.05% CAGR Shift
By PW Consulting, 2026-09-21
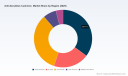
The Anti-Decubitus Cushions Market: Strategic Trends, Competitive Positioning, and Commercial Opportunities Through 2032
Understanding the Current Market Landscape
The global anti-decubitus cushions market has entered a phase of steady expansion, driven by evolving patient care standards, aging demographics, and a growing emphasis on pressure injury prevention across healthcare and home-care settings. From 2020 through 2025, the sector experienced consistent growth, supported by rising institutional procurement of specialized seating solutions and expanding clinical recognition of pressure redistribution technologies. By 2025, the market reached a revenue base that reflects both mature product adoption in established healthcare systems and incremental penetration in emerging care environments. Moving forward, the forecast period through 2032 points toward a sustained mid-single-digit compound annual growth trajectory, indicating that demand is not merely cyclical but structurally anchored in long-term care requirements.
Outdoor Cushions Market
This growth pattern, however, is not uniform. The market continues to navigate a transition from standardized, commoditized cushion designs toward differentiated, risk-stratified solutions that address varying pressure injury severities, patient mobility profiles, and care settings. At the same time, distribution channels, reimbursement pathways, and procurement cycles remain complex, creating barriers to rapid scaling for manufacturers and suppliers alike. Understanding where value is created and where friction persists is essential for executives evaluating market entry, portfolio expansion, or supply chain repositioning.
Core Challenges and Inflection Points
Three structural challenges currently shape the market's trajectory and determine which players can convert volume growth into sustainable margin expansion.
PW Consulting
- Regulatory and compliance fragmentation continues to influence product development cycles and market access. Cushions intended for wheelchair seating and pressure redistribution must satisfy multiple technical and safety expectations, including flammability requirements, washability standards, and performance benchmarks for seating stability and pressure distribution. While certain categories benefit from streamlined premarket pathways, manufacturers still face establishment registration, listing obligations, and the need to maintain documentation that supports clinical procurement and reimbursement eligibility. This layered compliance environment increases time-to-market for new designs and places a premium on regulatory agility.
- Reimbursement architecture and purchasing dynamics create uneven demand visibility. Pressure-reducing support surfaces, including anti-decubitus cushions, are covered under durable medical equipment benefit structures, but actual utilization depends on regional policies, institutional formularies, and cost-containment pressures within healthcare budgets. Buyers often evaluate total cost of ownership, replacement frequency, and clinical outcomes rather than unit price alone, which pushes suppliers to demonstrate value beyond basic pressure relief. This dynamic can slow adoption of premium or specialized designs in cost-sensitive procurement environments, even when clinical rationale is clear.
- Material performance and durability expectations are rising as care settings demand longer service life and consistent skin-contact safety. Products relying on gel inserts, air cells, and foams must balance load distribution, contour adaptation, and resistance to wear while maintaining hygiene and inspection compatibility. As clinical protocols increasingly emphasize proactive pressure injury prevention, the tolerance for inconsistency in cushion performance narrows, forcing manufacturers to refine material selection and quality control rather than compete primarily on price.
Key Demand Drivers Reshaping the Market
Several interconnected forces are expanding the addressable market and altering how suppliers compete. Understanding these drivers helps clarify where growth is likely to concentrate and which capabilities will differentiate future winners.
Technical Innovation and Performance Differentiation
Innovation is shifting from generic cushion construction toward engineered solutions that align with patient risk levels and clinical use cases. Alternating-pressure designs, vertical air-cell architectures, and hybrid foam-and-gel configurations illustrate how manufacturers are tailoring products to specific pressure redistribution goals and positioning needs. These design choices are not cosmetic; they directly affect how effectively a cushion maintains tissue perfusion, reduces shear, and supports prolonged seating without compromising user comfort or caregiver handling.
Material requirements are also becoming more specific. Medical-grade polyurethane, structured foam layers, and air-cell systems must deliver durability, skin-contact safety, and predictable performance over repeated use and cleaning cycles. In parallel, manufacturers are increasingly designing for inspectability and launderability, recognizing that hygiene protocols and routine checks are integral to pressure injury prevention programs. The cumulative effect is a market where engineering rigor and documented performance characteristics increasingly influence purchasing decisions, particularly in higher-acuity or institutional environments.
Policy, Reimbursement, and Standards Alignment
The policy environment plays an outsized role in shaping demand stability. Because pressure-reducing support surfaces are positioned within durable medical equipment coverage frameworks, manufacturers and distributors must continuously align product attributes with coverage logic and procurement criteria. Even when certain device categories are treated with lighter premarket burdens, market access still depends on registration, listing compliance, and the ability to support end-user justification. This creates a structural requirement for transparent product documentation and clear alignment with clinical use cases.
Standards further influence competitive positioning. Performance expectations around seating stability, pressure distribution, and safety characteristics compel suppliers to maintain consistent validation processes. Where standards are well understood and broadly adopted, they can reduce uncertainty and accelerate procurement decisions. Where expectations differ across regions or care settings, they can fragment product roadmaps and increase the operational cost of serving multiple markets. For executives, the practical implication is that regulatory and standards alignment is not a back-office concern; it is a commercial differentiator that affects win rates, channel partnerships, and expansion timing.
Demand-Side Changes in Care Delivery and End-User Behavior
Demand patterns are evolving as care shifts across hospital, rehabilitation, residential, and home environments. Prolonged sitting associated with wheelchair use, supportive seating needs, and positional management requirements create multiple application pathways for anti-decubitus cushions. At the same time, clinical awareness of pressure injury prevention has increased the emphasis on proactive seating solutions rather than reactive treatment. This shift encourages earlier adoption and broader usage across patient populations that may have previously been underserved by standard seating options.
End-user behavior is also changing. Institutions and individual buyers increasingly weigh practical usability, maintenance requirements, and replacement cycles when selecting cushions. A product that performs well in isolation but is difficult to clean, inspect, or fit within existing seating systems may lose out to a moderately less advanced alternative with better workflow compatibility. As a result, manufacturers that integrate ergonomic fit, ease of maintenance, and compatibility with common seating platforms are better positioned to convert clinical desirability into commercial adoption.
Supply Chain Realities and Cost Structure Pressures
The supply side of the market continues to face pressures that influence pricing, product design, and margin management. Raw material selection for air cells, foams, and gel components affects not only performance but also sourcing complexity and production consistency. Manufacturers must manage variability in material availability, processing requirements, and quality assurance while maintaining cost structures that remain acceptable to procurement teams.
At the same time, value migration is occurring toward designs that justify their cost through durability and reduced replacement frequency. In a market where buyers evaluate long-term outcomes and total cost of ownership, suppliers that can demonstrate reliable performance over time may have more room to defend pricing than those competing on short-term unit cost alone. This dynamic is particularly relevant for companies seeking to expand into higher-specification segments or to build trust with institutional buyers who prioritize consistent outcomes over occasional cost savings.
Competitive Landscape and Leading Strategic Postures
The market is characterized by a moderately concentrated competitive structure, with leading players holding meaningful but not dominant shares. This concentration level suggests that scale alone does not guarantee advantage; rather, differentiation through product design, clinical positioning, and channel execution often determines commercial outcomes. Several established companies illustrate distinct strategic approaches within the sector.
Diversified Pressure Care Offering
Some market participants emphasize a broad pressure care portfolio that addresses high-risk patient groups and intelligent pressure management. Companies in this segment often focus on alternating-pressure designs and air-based cushion systems engineered to redistribute load and reduce ulcer risk. By building product lines around specific risk profiles and seating requirements, these suppliers position themselves as solutions providers rather than commodity cushion manufacturers. Their advantage lies in the ability to match product design to clinical need, which can strengthen adoption among care teams seeking targeted pressure redistribution and positioning support.
Specialized Seating and Positioning Expertise
Other players concentrate on seat cushion geometry, vertical air-cell configurations, and positioning-focused designs. These products are developed with an emphasis on reducing pressure injuries in higher-risk scenarios while maintaining stability and pressure redistribution performance. A positioning-oriented approach can resonate in environments where seating alignment, patient stabilization, and injury prevention are equally important. Manufacturers pursuing this path often differentiate by aligning cushion design with practical use requirements, including compatibility with wheelchair systems and ease of inspection or cleaning.
Integrated Mobility and Seating Ecosystems
A further strategic posture involves integrating cushion solutions into broader mobility and seating ecosystems. Companies with strong wheelchair or seating platform presence often leverage their distribution relationships, service networks, and product compatibility to support cushion adoption. Gel and foam insert designs, along with contoured support options, are used to address pressure ulcer prevention and body contour needs within an existing equipment framework. This ecosystem approach can reduce friction for end users, since cushions that fit well with established seating products are easier to specify and deploy.
Air-Cell and Redistribution-Focused Positioning
Certain manufacturers build competitive advantage around air-cell cushion lines designed for optimal pressure redistribution and anti-decubitus protection. Custom and standard configurations allow these suppliers to address varying patient requirements while maintaining a consistent design philosophy centered on load management. This product-centric strategy can be particularly effective in segments where pressure redistribution performance is the primary purchasing criterion and where clinicians or procurement teams seek proven cushion mechanics rather than broader portfolio breadth.
How the Competitive Landscape Is Evolving
The market is likely to continue evolving along several directions. One is gradual consolidation among suppliers seeking to capture broader seating and pressure-care value chains, especially where integrated product compatibility and service coverage can improve customer retention. Another is segmentation, with manufacturers narrowing their focus to particular applications, risk levels, or care settings in order to differentiate on performance rather than price. A third is the ongoing entry of specialized players that bring novel material approaches, ergonomic designs, or digital-adjacent support services into the category. In each case, the central question for executives is whether scale, specialization, or ecosystem integration will create more durable advantage in their target segments.
Forward-Looking Trends and Associated Opportunities
Looking ahead three to five years, the market is expected to be shaped by a small number of high-impact trends that will influence product roadmaps, channel strategy, and investment priorities.
Trend One: Greater Emphasis on Risk-Stratified Seating Solutions
As pressure injury prevention becomes more systematically integrated into care protocols, demand may progressively shift toward solutions matched to specific patient risk profiles rather than one-size-fits-all cushioning. This trend creates opportunity for manufacturers that can document differential performance across use cases and communicate clearly how a given design fits a particular clinical scenario. It also raises the importance of clinical support materials, fit guidance, and application-specific product information in procurement decisions.
Trend Two: Increased Weight on Durability, Hygiene, and Lifecycle Economics
Institutional buyers and home-care users are likely to place greater emphasis on replacement cycles, cleaning compatibility, and long-term performance stability. Products that maintain pressure redistribution characteristics over repeated use, support inspection requirements, and withstand laundering or maintenance routines may gain preference in environments where caregiver time and operational consistency matter. Suppliers that invest in lifecycle design and quality consistency can use these attributes to strengthen value propositions beyond initial purchase price.
Pressure Ulcer Treatment Products Market
Trend Three: Broader Integration with Seating Platforms and Procurement Pathways
The market may increasingly reward cushion designs that align with existing wheelchair and seating ecosystems, as well as with prevailing procurement and coverage logic. Compatibility, fit consistency, and documentation that supports reimbursement or institutional specification can reduce adoption barriers. For suppliers, this suggests value in building partnerships, service support, and product-range coherence that make selection and deployment easier for end users and intermediaries. At the same time, differences in regional reimbursement and standards environments may continue to shape where and how quickly new products scale.
Risks and Uncertainties to Monitor
Several factors could temper or redirect these trends. Changes in coverage interpretation, procurement tightening, or shifts in institutional budgeting could slow adoption of higher-cost designs. Material supply variability and manufacturing consistency challenges may affect product reliability if not managed carefully. In addition, the balance between standardization and specialization will remain contested; too much segmentation can limit economies of scale, while too much standardization can weaken clinical relevance. Executives should track these uncertainties as part of market planning rather than treating growth as automatically linear.
Strategic Implications for Decision Makers
For executives operating in or evaluating this market, the priority is to align product strategy and commercial positioning with the market's actual decision drivers: clinical relevance, durability, compliance support, and integration into care workflows. The following considerations may help structure near-term actions.
- For manufacturers and product developers: Focus engineering and documentation efforts on clearly defined application needs rather than broad, undifferentiated product lines. Where possible, design for inspectability, cleaning compatibility, and seat-platform fit, since these attributes increasingly influence repeat procurement and institutional acceptance. Align validation and material selection with the performance expectations that procurement teams and clinicians use when comparing options.
- For investors and strategic acquirers: Evaluate opportunities based on differentiation quality, reimbursement alignment, and channel leverage rather than headline volume alone. In a market with moderate concentration, value creation often depends on whether a company can maintain pricing power through demonstrable performance, reduce customer switching through compatibility and service, and scale without compromising quality or compliance readiness.
- For procurement leaders and care providers: Evaluate cushions against total use-case performance, including pressure redistribution effectiveness, maintenance burden, replacement expectations, and compatibility with existing equipment. A lower unit cost may be offset by shorter service life or workflow friction. Where possible, standardize selection criteria around clinical outcomes and operational feasibility to simplify sourcing and reduce inconsistent purchasing across sites or departments.
Conclusion
The anti-decubitus cushions market is moving through a period in which growth is supported by structural care needs, but competitive advantage is increasingly determined by how well suppliers translate clinical requirements into usable, durable, and compliant seating solutions. The companies that fare best over the next several years are likely to be those that treat product performance, standards alignment, and procurement reality as interconnected commercial issues rather than separate technical or regulatory matters. As segmentation deepens and end users place greater weight on lifecycle value, the opportunity lies in building offerings that are not only effective in principle but also practical to specify, maintain, and sustain in real care environments.
For detailed analysis of this topic, please visit the official page: Anti-decubitus Cushions Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Power Cords & Extension Cords Market: 6.2% CAGR Trajectory Changes Everything
By PW Consulting, 2026-09-21
The Power Cords & Extension Cords Market: Strategic Shifts and Commercial Opportunities (2026–2032)
The global market for power cords and extension cords has matured into a sector defined by steady value accumulation, structural segmentation, and incremental but consequential regulatory change. Over the 2020–2025 period, revenue expanded from roughly $3.26 billion to $4.4 billion, establishing a trajectory that carries forward into the 2026–2032 forecast window. The extended outlook points to a compound annual growth rate of 6.2%, lifting projected revenue to approximately $6.68 billion by 2032. This pace is neither explosive nor stagnant; it reflects a market where demand fundamentals are broad-based, yet growth is increasingly tied to differentiation in safety, performance, and application-specific engineering.
Regional activity illustrates a market that is geographically diversified but unevenly developed. North America and Asia Pacific together anchor the largest revenue pools, reflecting mature commercial construction patterns, dense electronics ecosystems, and sustained household demand. Europe remains a substantial contributor, shaped by localized certification regimes and building practices. Latin America and the Middle East/Africa represent smaller but expanding bases, often driven by infrastructure investment, urbanization, and gradual formalization of electrical supply chains. Rather than signaling saturation, the geographic spread highlights where product configuration, voltage standards, and certification pathways must be managed with precision.
The market is structurally split across indoor, outdoor, and heavy-duty product families. Indoor configurations hold the largest share, supported by continuous deployment in homes, offices, and light commercial environments. Outdoor solutions form a smaller but resilient segment tied to construction, outdoor equipment, temporary power setups, and seasonal demand cycles. Heavy-duty cords occupy a distinct position, serving industrial use, medical-adjacent environments, and settings where thermal stress, abrasion resistance, and mechanical durability are non-negotiable. Application-side demand also divides across residential, commercial, and industrial channels. Residential remains the largest demand base, commercial contributes a meaningful mid-tier volume, and industrial represents a specialized segment that rewards higher engineering rigor and compliance confidence.
Key Challenges and Inflection Points
A market growing at a consistent mid-single-digit rate can still feel pressure at the margin. Three challenges stand out as current inflection points. First, raw material volatility is reshaping cost expectations. Price movements in PVC and related polymer inputs have introduced variability in production economics, especially for manufacturers balancing export competitiveness with domestic cost structures. The gap between regional input prices has become more than a procurement issue; it now influences margin planning, inventory strategy, and the timing of price adjustments to downstream customers.
Second, safety and certification requirements are tightening in ways that alter product design and time-to-market. Recent revisions to the UL 817 standard for cord sets and power-supply cords, including new provisions for heater-use power-supply cords, reflect a broader push toward clearer performance expectations in higher-load and thermally sensitive applications. For manufacturers, this is not merely a compliance update. It changes testing protocols, documentation practices, and the engineering margin needed to remain acceptable across North American and internationally harmonized channels.
Third, the market faces an identity challenge around commoditization versus specialization. Many product forms are still viewed as interchangeable, especially in price-sensitive consumer channels. Yet the highest-value opportunities increasingly reside in application-specific performance, traceability, and certification clarity. Companies that compete primarily on generic specifications risk margin compression, while those building defensible positions around medical-grade, industrial-grade, or custom cord sets are better positioned to protect pricing and customer retention.
Key Drivers Reshaping Market Trajectory
The 6.2% CAGR over the forecast horizon is not simply a continuation of past momentum. It reflects structural drivers that interact with one another: technology, regulation, demand-side behavior, and cost architecture. Understanding how these forces converge is essential for deciding where to invest, where to build capability, and where to exercise caution.
Innovation in Materials, Plug Geometry, and Application-Specific Design
One of the more durable drivers is incremental engineering innovation. Power cord and extension cord demand is not only increasing in volume; it is becoming more exacting in specification. This includes better insulation and jacket formulations that balance flexibility, flame resistance, and thermal endurance. It also includes design improvements in connector geometry, strain relief, and cord organization, which matter in both residential convenience and commercial durability. In data center-adjacent and hospital-adjacent settings, where cord integrity is tied to uptime and safety, even modest improvements in strain management, labeling, and configuration consistency can influence procurement decisions.
A second innovation theme is the broadening of purpose-built product families. Heavy-duty and outdoor configurations continue to gain relevance in applications where exposure, repeated flexing, and mechanical stress are routine. Medical-grade and hospital-grade cord sets represent a narrower but higher-stakes segment where performance documentation and certifiable consistency can become competitive differentiators. Custom wiring harnesses and OEM-tailored solutions extend the market beyond standardized retail SKUs into value-added configurations that are less vulnerable to direct price comparison.
Regulatory and Certification Dynamics
Regulatory expectations are becoming a more explicit part of market strategy. Certification is already central to many channels, but recent standard revisions are adding precision around higher-risk use cases. The July 30, 2025 revision of UL 817 introduced new requirements for heater-use power-supply cords, signaling that regulators are paying closer attention to load conditions where thermal management becomes critical. This matters because heater-related applications often operate near the upper bounds of common cord capabilities, where small specification gaps can become safety or reliability concerns.
For companies with North American exposure, UL alignment is a market-access prerequisite in many cases and a competitive trust signal in others. For internationally oriented manufacturers, the challenge is maintaining certification readiness across multiple regulatory regimes while keeping product families efficient enough to avoid over-fragmentation. The practical effect is that compliance is no longer a back-office function; it is increasingly part of product strategy, marketing credibility, and channel access.
Demand-Side Shifts in Residential, Commercial, and Industrial Use
Demand behavior is evolving on both the consumer and enterprise sides. In residential settings, the growth of home offices, entertainment setups, and smart-home devices continues to support accessory demand. Extension cords and power strips are no longer treated solely as temporary utilities; they are being chosen for cord length, barrier compatibility, aesthetic integration, and perceived safety. In commercial environments, demand is shaped by office refurbishment, retail upgrades, hospitality turnover, and the ongoing need for flexible power distribution during fit-outs and reconfigurations.
Industrial demand plays a different role. It is less about volume expansion and more about reliability, specification discipline, and supply assurance. Factories, maintenance operations, and facilities teams often prioritize cords and cord sets that can withstand repeated use, environmental exposure, and inspection regimes. As industrial procurement becomes more selective, the value shifts toward documentation, consistency, and the ability to match cord sets to specific equipment and site conditions.
Supply Chain and Cost Structure Pressures
Cost structure remains a pivotal driver because it influences both competitiveness and product strategy. Recent pricing movements in PVC illustrate how material economics can diverge by region. In April 2026, China PVC prices were reported near $735.45 per metric ton, while U.S. PVC prices were reported at $822.45 per metric ton. That spread matters for manufacturers operating across export and domestic channels, because it affects landed cost, relative pricing power, and the attractiveness of localization versus import-based supply.
Beyond raw materials, the supply chain is also being shaped by the need for resilience. Procurement teams increasingly value supplier stability, lead-time predictability, and the ability to support custom configurations without excessive turnaround penalty. As a result, some buyers are willing to accept differentiated pricing if it is paired with dependable certification support, batch consistency, and timely delivery. This is gradually shifting the market from pure cost competition toward a more balanced evaluation of cost, risk, and performance assurance.
Competitive Landscape and Leading Strategies
The competitive field is broad, with participants spanning large North American and European manufacturers, Indian electricals players, and specialized Asian cord-set producers. What distinguishes the more successful players is not simply scale, but the ability to align product families with the market’s growing emphasis on safety, application specificity, and configuration flexibility.
Southwire Company LLC occupies a strong position in building wire and cable, including extension cords used in utility, industrial, and commercial applications. Its profile reflects a broad distribution footprint and familiarity with the requirements of installation, infrastructure, and commercial construction markets. For Southwire, the strategic advantage lies in combining product breadth with the credibility needed to serve demanding channel requirements.
Volex plc represents a more globally integrated model, manufacturing power cords, plugs, connectors, and custom wiring harnesses for consumer, industrial, and data center-related uses. Its broad configuration capability supports customers that need standardized solutions and tailored assemblies alike. The strategic implication is that cord-set suppliers with harness and connector expertise can capture additional value by addressing OEM and facility needs beyond simple off-the-shelf cords.
Havells Ltd and Goldmedal Electricals both illustrate the strength of electricals-focused manufacturers in India, with product lines spanning home electricals, extension cords, flexible cables, switches, and power accessories. Their relevance comes from serving both residential and commercial channels with products that balance affordability and practical reliability. In these markets, scale in distribution, brand recognition, and breadth across electrical accessories can be as important as cord-specific engineering.
In China, Ningbo Biaoda Electric Co., Ltd., Jiaxing Hongzhou Cable Co., Ltd., and similar specialized manufacturers reinforce the region’s role as a production base for power cords, power boards, extension cords, and power strips. Their competitive strength typically lies in manufacturing efficiency, configuration variety, and export readiness. The challenge for these players is converting cost and volume advantages into durable positioning, particularly as buyers pay closer attention to certification, traceability, and application suitability.
Taiwan-based YFC-Boneagle Electric Co., Ltd. adds a further dimension through global exports of power cords, cord sets, LAN cables, and networking accessories. Its export-oriented profile underscores how regional manufacturers can compete internationally by aligning with end-market requirements in connectivity and power distribution.
On the U.S. and specialty side, Kord King, Electri-Cord Manufacturing, Webber Electronics, Inc., Z-Tronix Inc., and Quail Electronics, Inc. illustrate a different competitive logic. Kord King’s emphasis on premium cords, medical-grade, heavy-duty, and construction-grade cord sets shows how a manufacturer can pursue higher-margin positioning by aligning with demanding use cases. Electri-Cord Manufacturing’s focus on domestic, international, and hospital-grade cords reinforces the same theme: specialty certification and application specificity can create defensible niches. Webber Electronics combines international, North American, hospital-grade, and GFCI power cords across medical, industrial, dental, and commercial markets, reflecting the importance of multi-standard readiness and sector-targeted product lines. Z-Tronix and Quail Electronics extend this pattern with OEM, industrial, commercial, and international configuration capabilities, including custom power cords and cord sets. Their presence suggests that serving both standard and custom requirements can be a practical way to diversify demand while maintaining deeper customer relationships.
PW Consulting Information & Electronics Research Center
Strategic Positioning and Differentiation
Across these companies, several strategic patterns are emerging. One is the move toward application-specific credibility. Manufacturers that can demonstrate consistent performance in medical, industrial, or higher-load contexts are better positioned to escape pure price competition. Another is the blending of standardization with customization. Companies offering both standard cord sets and tailored configurations can capture broader demand while preserving relationships with customers who need tailored specifications. A third pattern is certification readiness as a competitive asset, especially where UL and other standard alignments affect purchasing confidence and channel access.
Market Structure and Evolution
Market concentration remains moderate. A collective concentration reading shows that the top three participants account for roughly 28.5% of the market, while the top five reach about 39.2%. This suggests a field that is not dominated by a small number of incumbents, but still features meaningful leadership positions. The structure leaves room for both consolidation and specialized entry.
Consolidation is plausible in segments where distribution scale, certification infrastructure, and cost discipline matter increasingly. New or expanding entrants can still find openings by focusing on underserved configurations, niche certification needs, or regional demand that is not fully served by larger players. At the same time, the low-concentration structure means that brand trust, product reliability, and compliance documentation can be decisive in purchasing decisions, particularly when buyers compare otherwise similar offerings.
Future Trends and Commercial Implications (2026–2032)
Looking ahead, the market’s direction is unlikely to be driven by a single breakthrough. More likely, it will be shaped by the compounding effect of specification tightening, demand fragmentation, and cost-aware procurement. Three trends are especially relevant for decision-makers.
First, application-specific certification and documentation will become more central to product competitiveness. As revisions such as the UL 817 update for heater-use power-supply cords take effect, buyers in higher-load or higher-risk environments will likely increase scrutiny on whether cords are explicitly appropriate for the intended use. This favors manufacturers that can provide clear guidance, consistent batch quality, and reliable conformity evidence.
Second, cost and material volatility will continue to reward supply chain discipline. With regional PVC pricing divergence and broader input variability, companies that can manage inventory, hedging, sourcing mix, and localized production more effectively will have an advantage in protecting margins without sacrificing service levels. This may also encourage more regionalized production or supplier diversification in response to regional cost differentials.
Wireless Chargers & Power Cords and Portable or Wearable Charging Cable Market
Third, demand will continue to fragment across more specialized use cases, increasing the importance of configuration capability. Residential convenience products will persist at scale, but commercial and industrial buyers will increasingly value solutions tailored to equipment, environment, and installation constraints. That creates opportunities for cord-set suppliers that combine standard SKUs with custom engineering, especially where connectors, cord length, jacket type, and certifying marks must be aligned to specific procurement standards.
Risks and Uncertainties
These opportunities are not risk-free. Regulatory evolution can accelerate and vary by region, imposing additional testing and documentation burdens that disrupt product rollouts if compliance systems are not prepared. Raw material price swings may compress margins more quickly than pricing adjustments can recover them, particularly for manufacturers with limited flexibility in sourcing or product mix. There is also the persistent risk that certain consumer-facing categories remain commoditized for longer than anticipated, making volume growth dependent on distribution strength and promotional intensity rather than value-based differentiation.
Another uncertainty lies in the pace of channel consolidation among buyers. If procurement becomes more centralized and specification-driven, smaller suppliers may face higher barriers to entry unless they can demonstrate clear technical or certification advantages. Conversely, if buyers continue to value flexibility and responsiveness, specialized suppliers may retain a strong position even in a moderately concentrated market.
Actionable Recommendations for Decision-Makers
For manufacturers, the central question is whether product strategy is built around interchangeable volume or defensible specialization. The more durable path is to align at least part of the portfolio with higher-trust applications and clearer certification requirements. That could mean investing in medical-grade or industrial-grade offerings, strengthening documentation for heater-use and other higher-load applications, and ensuring that connector and cord configurations are developed with end-use conditions in mind rather than generic specifications alone. It also means checking whether cost structures can absorb regional material volatility without forcing reactive price moves that erode customer trust.
Appliance Power Cord Market
For investors, the market offers a mix of steady growth and selective upside. Broad exposure may be attractive for its consistency, but the most meaningful value creation is likely to come from companies that demonstrate certification readiness, application specificity, and the ability to serve custom or higher-specification demand. Due diligence should pay attention to whether a company’s product mix is concentrated in price-sensitive commodity segments or balanced with segments that justify stronger pricing and longer customer retention. Supply-chain resilience and regional cost positioning should also be evaluated, given the divergence in raw material pricing and its effects on competitiveness.
For procurement and supply chain leaders, the priority is to treat cord and cord-set purchasing as a specification and risk decision, not solely a unit-cost decision. Evaluations should include suitability for the intended application, certification alignment, traceability, and the supplier’s ability to support standard and custom configurations without unacceptable lead-time penalties. Where operations involve higher loads, medical contexts, or industrial conditions, the cost of qualification errors can exceed the apparent savings from choosing the lowest-priced option. Supplier stability and documentation quality are therefore part of the value equation, not optional extras.
The broader takeaway is that the power cords and extension cords market is changing in ways that reward preparedness. The growth path is solid, but the competitive winners will be those who interpret regulation, cost volatility, and demand fragmentation as strategic signals rather than background noise. For organizations that need detailed segmentation, regional cost dynamics, and application-level demand patterns to refine their plans, deeper commercial intelligence can shorten the gap between high-level strategy and executable action.
For detailed analysis of this topic, please visit the official page: Power Cords & Extension Cords Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Cheque Scanner Market: Why the 5.6% CAGR and APAC Shift Change Everything
By PW Consulting, 2026-09-21
Strategic Trends and Commercial Opportunities in the Cheque Scanner Market
The global cheque scanner market has entered a phase of steady structural expansion, driven by the ongoing digitization of financial back-office operations and the gradual modernization of check processing infrastructure. By 2025, the market has crossed a significant revenue milestone, with industry data placing the total market size at approximately $1 billion. Looking ahead to a forecast period spanning 2026 through 2032, the sector is projected to grow at a compound annual growth rate of 5.6 percent, reaching a multi-billion-dollar valuation by the end of the decade. While this growth trajectory may appear measured in percentage terms, the underlying dynamics reveal a market undergoing meaningful technological maturation, regulatory alignment, and shifting usage patterns across geographic and operational segments.
Document Scanner Market
The historical progression from 2020 through 2025 illustrates a consistent upward curve, reflecting incremental investments by banks and financial institutions to replace legacy handling methods with intelligent imaging solutions. The forecast period suggests that this momentum will continue, albeit with shifting drivers as the market moves from early adoption phases into more mature deployment cycles. As the installed base expands and end-user expectations around speed, image fidelity, and remote processing capabilities evolve, manufacturers and solution providers face an increasingly nuanced landscape where differentiation depends less on basic scanning functionality and more on integration, workflow optimization, and compliance readiness.
Market Maturity and Core Challenges
Operational Scale and Legacy Transition Pressure
One of the defining characteristics of the current market environment is the tension between established processing habits and the operational need to accelerate digitization. Cheque scanners are no longer viewed simply as point hardware; they are components of broader capture ecosystems that must interact with network infrastructure, image quality standards, and downstream processing workflows. Institutions deploying these systems are balancing the need to reduce physical check handling time with the reality that many branches and back-office environments still operate with heterogeneous equipment, varying floor space constraints, and different throughput requirements. This creates a challenge for vendors seeking scalable deployment models and for buyers who must justify standardization across multiple locations.
A second challenge lies in aligning hardware innovation with regulatory expectations. Image quality and data retention requirements have become embedded in the operational fabric of check processing. Systems must not only scan efficiently but also produce images that satisfy established transmission and retention protocols. This regulatory backdrop raises the technical bar for new entrants and reinforces the importance of long-term compatibility, which in turn favors manufacturers with sustained product development roadmaps and robust service networks.
Fragmentation and Coordination Across Use Cases
A third pressure point is the uneven pace of adoption across different operational settings. Some environments prioritize high-volume teller capture and centralized processing, while others require compact desktop solutions that can support distributed branch operations or remote deposit workflows. The coexistence of these divergent needs complicates product strategy, as manufacturers must balance volume-oriented engineering with user-friendly, low-footprint designs. At the same time, end-users are increasingly evaluating scanners as part of broader cost-efficiency and processing-time initiatives, meaning that purchase decisions are increasingly tied to total workflow performance rather than unit-level features alone.
Core Drivers Shaping Market Direction
Technological Innovation and Processing Accuracy
Technological advancement remains one of the most visible catalysts for demand. Modern scanning platforms are being engineered to improve MICR reading accuracy, enhance image capture under varied conditions, and support faster throughput without sacrificing image quality. Recent product introductions illustrate how manufacturers are responding to these expectations. In late 2025, Digital Check Corp. introduced the next-generation TellerScan TS250 UV ultraviolet cheque scanner, succeeding the TS240 model and designed for distribution through its global reseller network. Alongside this, the company emphasized updated CheXpress CX35 and CX35-Network models featuring a zero-footprint design and Smart Button technology. These updates signal a broader industry shift toward compact form factors, simplified operator interaction, and modularity that supports both localized and networked deployment scenarios.
The emphasis on ultraviolet imaging, network-capable configurations, and streamlined physical design reflects a market that is increasingly attentive to space constraints, operator ergonomics, and the ability to integrate scanning into digitally connected branch environments. As imaging specifications become more tightly aligned with downstream processing requirements, scanner performance is evolving from a stand-alone specification into a workflow enabler.
Regulatory Frameworks and Image-Based Clearing Standards
Policy and regulatory frameworks continue to play a central role in shaping procurement behavior and technology requirements. The Check Clearing for the 21st Century Act has provided the legal foundation for image-based clearing, requiring participating institutions to maintain image retention capabilities and implement standardized transmission protocols. This framework has helped accelerate the transition toward digital check processing by giving institutions a clear regulatory basis for moving away from purely physical handling.
Complementing that foundation, Federal Reserve guidelines have established minimum image quality standards for check processing, setting technical specifications that modern scanners must satisfy. These quality mandates have practical commercial consequences: they influence product specifications, encourage consistent image output across different environments, and raise the importance of compliance-grade engineering. For manufacturers, this means that competitive advantage increasingly depends on delivering hardware that reliably meets regulatory image expectations while also reducing operator error and rework.
Demand-Side Behavior and Branch-Level Efficiency Goals
Demand-side dynamics are being reshaped by institutional priorities around processing speed, cost control, and branch-level efficiency. U.S. banks process, analyze, and clear a large volume of checks each day, and many are installing scanners at various branches to shorten the overall clearing cycle. This operational push aligns with broader government guidance that encourages the use of digital checks and image-based workflows. As a result, scanner adoption is increasingly tied to measurable time savings, reduced manual intervention, and faster reconciliation.
At the same time, demand is not limited to large centralized banking operations. Distributed environments that require remote deposit capture and localized image acquisition are also contributing to purchasing activity. This broadening usage profile is encouraging vendors to develop solutions that can serve both high-volume teller environments and smaller-scale branch or back-office settings, creating a more diverse demand base than in earlier phases of market development.
Cost Structures and Deployment Economics
Cost considerations continue to influence how quickly and broadly scanner technology is adopted. Institutions weigh not only upfront hardware expenditure but also installation complexity, maintenance demands, and the ability to standardize devices across sites. The growing availability of network-enabled and space-efficient models is reshaping these economics by reducing some of the physical and operational friction associated with deployment. When a scanner can be integrated into existing branch layouts without extensive floor space requirements, and when it can interface cleanly with capture workflows, the total cost of adoption becomes more attractive relative to the operational benefits it delivers.
PW Consulting Automotive & Machinery Research Center
Supply-side dynamics also matter. Manufacturers with established distribution channels and global reseller networks are better positioned to scale new models efficiently, while those with broader imaging and document capture portfolios can offer complementary capabilities that strengthen the value proposition for end-users seeking integrated solutions.
Competitive Landscape and Leading Strategies
Established Players and Product-Line Differentiation
The competitive field is shaped by a mix of specialized cheque scanner manufacturers and broader imaging and financial systems providers. Digital Check Corp., headquartered in Northbrook, Illinois, continues to emphasize teller capture, remote deposit, and high-volume production imaging through products such as the CheXpress CX35 and TellerScan TS250 series. Its recent product moves highlight an emphasis on refreshed imaging features, network-ready configurations, and reseller-led distribution, reinforcing a strategy centered on product continuity and broad availability.
Panini S.p.A., based in Turin, Italy, positions itself around intelligent cheque scanners such as the EverneXt and Vision X lines, targeting distributed check capture and remote deposit applications. Its approach reflects an orientation toward intelligent capture functionality and flexibility across deployment contexts. Epson America, Inc. offers desktop models like the TM-S1000II and TM-S1000II-NW, combining MICR reading with RDC and back-office capture features, while Canon U.S.A., Inc. supports the imageFORMULA CR-series for desktop and check transport imaging. These players illustrate how established imaging brands leverage document capture expertise to compete in cheque scanning by emphasizing reliability, ergonomic design, and integration with broader office or branch imaging ecosystems.
Currency Count Machine Market
Banking-Centric and Systems-Integrated Approaches
Other competitors bring a stronger systems-integration orientation. ARCA Tech Systems, LLC provides LS40 and LS100 scanners for teller and remote deposit capture, while RDM Corporation supplies network-focused models such as the EC9000i and EC9600i for image capture and MICR applications. NCR Voyix Corporation aligns cheque scanning with broader banking and retail capture systems, positioning scanners as components of integrated financial processing environments rather than standalone devices.
This divergence in positioning matters strategically. Some manufacturers compete primarily on hardware refinement and product-line breadth, while others compete on integration, workflow compatibility, and the ability to match scanner capabilities to institutional capture systems. A market concentration measure indicates that the top three firms account for roughly 24.6 percent of revenue and the top five for about 26.2 percent, suggesting a landscape that remains relatively dispersed while still featuring recognizable leaders with distinct strategic identities.
Evolution of the Competitive Structure
The competitive structure appears to be evolving along several axes. One is the continued refinement of product families to serve both centralized and distributed use cases. Another is the increasing importance of compliance-grade image quality and network readiness as baseline expectations rather than premium differentiators. A third is the role of distribution and integration partnerships in extending reach, especially in environments where branch technology decisions are made in coordination with broader banking technology roadmaps.
New entrants and adjacent imaging brands may find opportunities in niche deployment scenarios or in specific geographic markets where regional service support and localized product features matter. At the same time, established players benefit from product maturity, regulatory familiarity, and existing relationships with financial institutions. The net effect is likely to be a market where competition intensifies not primarily through price alone, but through reliability, integration ease, and the ability to reduce operational friction in real-world branch and back-office settings.
Future Trajectory and Emerging Opportunities
Deeper Integration of Scanning into Digital Capture Workflows
Over the next three to five years, one of the most important trends is likely to be the further integration of cheque scanners into digitally connected capture workflows. As institutions continue to prioritize faster clearing cycles and reduced manual handling, scanners will increasingly be evaluated in relation to how well they support remote deposit capture, networked branch operations, and image-based reconciliation. This creates commercial opportunities for manufacturers that can offer hardware with strong compatibility, straightforward configuration, and predictable service requirements. It also creates opportunities for solution providers that can bundle scanning with workflow software, image quality assurance, and operational support.
Growth in Distributed and Space-Constrained Deployments
A second trend is the continued expansion of distributed capture models, especially in environments where compact, easy-to-deploy devices are preferred. The move toward zero-footprint designs and simplified operator controls suggests that end-users are placing greater value on branch-friendly equipment that can be installed without major layout changes. As a result, there may be growing demand for desktop and low-profile scanners that still meet image quality and MICR reading expectations. For manufacturers, this trend rewards engineering that balances performance with form factor, while for buyers it opens the door to broader standardization across locations with different physical constraints.
Regulatory Alignment as a Stable Demand Anchor
A third trend is the ongoing role of regulatory compliance as a stabilizing force behind procurement. Because image-based clearing frameworks and quality standards are embedded in operational practice, demand for scanners that satisfy these requirements is unlikely to disappear even if overall market growth moderates in certain periods. This creates a degree of structural resilience, but it also means that product roadmaps must keep pace with evolving image expectations and transmission protocols. Companies that treat compliance alignment as a core engineering priority rather than an add-on are better positioned to maintain continuity in purchasing environments where auditability and image retention remain critical.
Risk Factors and Uncertainty
Despite these favorable structural signals, several uncertainties bear watching. If macroeconomic conditions constrain institutional spending, procurement cycles may lengthen, particularly for non-essential hardware upgrades. If imaging standards or clearing protocols shift materially, manufacturers may need to adapt product specifications more quickly than anticipated. In addition, as more functions become digitized and centralized, certain branch-level capture needs could consolidate into fewer device categories, potentially intensifying competition among suppliers seeking to remain relevant across a narrower set of deployment scenarios. Finally, competitive pressure from adjacent imaging technologies and integrated capture platforms could limit standalone scanner growth in segments where end-users prefer bundled solutions.
Actionable Guidance for Decision-Makers
For Manufacturers and Product Leaders
Product strategy should prioritize three areas. First, keep image quality, MICR reliability, and network compatibility at the center of engineering roadmaps, since these capabilities increasingly function as baseline requirements rather than optional features. Second, invest in deployment-friendly design that reduces installation friction, especially for branch and distributed environments where floor space and setup simplicity matter. Third, strengthen channel and integration partnerships so that new models can reach end-users efficiently and align with broader capture ecosystems. Companies that can demonstrate measurable improvements in throughput, ease of use, and compliance-readiness will be better positioned to justify premium positioning in a market that is maturing but still expanding.
For Investors and Market Observers
From an investment perspective, the market's projected mid-single-digit growth path suggests a sector that is expanding steadily rather than erupting explosively, which makes differentiation and execution quality especially important. Attention should focus on manufacturers with clear product continuity, strong distribution reach, and proven alignment with banking workflow needs. It is also worth monitoring how integration-focused players and broader imaging brands compete for the same procurement budgets, since this can influence share dynamics across both specialized and conglomerate competitors. In this environment, value creation is likely to come from companies that can sustain relevance across multiple deployment models while adapting to regulatory and workflow evolution.
For Procurement and Banking Technology Buyers
For institutions evaluating scanner purchases, the priority should be to assess total workflow impact rather than device specifications in isolation. Key considerations include how well a scanner integrates with existing capture and processing systems, whether it meets applicable image quality expectations, how easily it can be standardized across locations, and what service and support model accompanies the hardware. Given the growing variety of form factors and network-capable options, procurement teams should also weigh whether compact desktop solutions, teller-oriented high-throughput units, or network-integrated devices best match the operational profile of each site. Aligning device selection with branch layout, processing volume, and compliance requirements can reduce implementation friction and improve long-term return on deployment.
As the market continues to evolve from basic scanning toward integrated, compliance-aligned capture environments, the strategic picture becomes more nuanced and more opportunity-rich for organizations that have access to detailed, up-to-date segmentation and competitive data. A deeper review of regional and application-level deployment patterns, product roadmap sequencing, and company-level positioning can help decision-makers translate broad market momentum into concrete procurement, investment, and product decisions. For those seeking a more granular view of these dynamics, the full PW Consulting research report provides expanded segmentation detail, competitive profiling, and customized strategic scenarios tailored to specific operational contexts.
For detailed analysis of this topic, please visit the official page: Cheque Scanner Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com